 WhatsApp
 Call Us
 Email Us
 Whatsapp Community

Would you like to schedule a call back
Global mobility has made cross-border taxation genuinely complicated. Whether you're an NRI, OCI holder, foreign national, expatriate, global executive, foreign investor, or multinational company, income earned across more than one country can end up taxable in more than one jurisdiction. Without proper planning, that can mean double taxation, additional compliance work, and unnecessary tax costs.
India has DTAAs with more than 90 countries, including the US, UK, Canada, UAE, Singapore, Australia, Germany, France, Japan, the Netherlands, Switzerland, Ireland, and many others. These treaties determine which country has the right to tax specific types of income and can provide relief through exemptions, reduced withholding rates, and Foreign Tax Credits.
At Dinesh Aarjav & Associates, we provide specialized NRI advisory services and international tax support for NRIs, foreign residents, overseas investors, multinational companies, startups, and globally mobile individuals. Our DTAA consultants assist with India-US, India-UK, India-Canada, India-UAE, and India-Singapore DTAA matters, along with Form 10F filing, Tax Residency Certificates, Foreign Tax Credit claims, Permanent Establishment analysis, royalty and FTS planning, cross-border investment structuring, and international tax compliance.
Our team of Chartered Accountants, US CPAs, Enrolled Agents, ACCAs, and international tax specialists helps clients structure their cross-border affairs efficiently while remaining compliant with the Income Tax Act, the Income Tax Act 2025, FEMA, and applicable international tax treaties
A Double Taxation Avoidance Agreement is a treaty between two countries designed to stop the same income being taxed twice. It sets out which country has the primary right to tax a given type of income, and provides the mechanism to eliminate or reduce the double hit.
Take an NRI in the US who earns rental income from a property in India that income could technically be taxed in both countries. The India-USA DTAA is what determines how it should actually be taxed and whether the taxpayer can claim relief through a reduced withholding rate or a Foreign Tax Credit.
DTAA provisions touch salary and employment income, business and professional income, rental income, dividends, interest, capital gains, royalties, Fees for Technical Services, pensions, director's remuneration, independent personal services, and shipping and air transport income. Exactly how each is treated depends on the specific treaty and your specific facts.
Cross-border taxation isn't just a multinational-corporation problem anymore; individuals routinely earn income from multiple countries through employment, investments, business ownership, rental property, retirement accounts, and digital businesses.
Skipping treaty planning can result in double taxation on the same income, excess withholding, incorrect TDS, delayed Foreign Tax Credit claims, unexpected Permanent Establishment exposure, royalty and FTS disputes, tax residency conflicts, litigation, lower investment returns, and higher compliance costs.
Our NRI DTAA advisory services help NRIs understand treaty eligibility, determine tax residency, claim reduced withholding rates, prepare Form 10F, obtain Tax Residency Certificates, plan Foreign Tax Credits, structure cross-border investments, correctly characterize income, plan capital gains, and maintain the documentation required to support treaty benefits and tax positions.
India runs one of the largest tax treaty networks in the world in more than 90 countries. We regularly work under treaties involving the US, Canada, and Mexico in North America; the UK, Germany, France, the Netherlands, Belgium, Luxembourg, Switzerland, Sweden, Norway, Denmark, Finland, Ireland, Italy, Spain, Portugal, Austria, Poland, and the Czech Republic in Europe; the UAE, Saudi Arabia, Qatar, Oman, Kuwait, and Bahrain in the Middle East; Singapore, Australia, New Zealand, Japan, South Korea, China, Hong Kong, Malaysia, Thailand, Indonesia, the Philippines, Vietnam, and Sri Lanka in Asia-Pacific; and South Africa, Mauritius, Kenya, Ethiopia, and Egypt in Africa.
Each treaty covers tax residency, business profits, Permanent Establishment, salary income, capital gains, dividends, interest, royalties, Fees for Technical Services, Foreign Tax Credits, Exchange of Information, and Mutual Agreement Procedures and no two treaties handle these identically. The India-USA DTAA, for instance, differs meaningfully from the India-UAE or India-Singapore treaties on royalties, technical services, and pensions, which is exactly why picking the right treaty article matters as much as knowing the treaty exists.
Avoiding double taxation is the whole point of the treaty, preventing the same income from being taxed twice in two different countries.
Lower withholding rates many treaties reduce the standard rate on dividends, interest, royalties, FTS, and certain capital gains.
Foreign Tax Credit tax already paid in one country can often be credited against what you owe in the other, cutting the overall bill.
More certainty treaties allocate taxing rights clearly, which cuts down on ambiguity and disputes.
Less litigation proper planning heads off disputes over residency, withholding, and cross-border income before they start.
Better investment structuring treaty provisions genuinely change how efficiently you can structure international investments.
Better cash flow and lower withholding means more liquidity and better net returns.
Cleaner compliance proper documentation, TRC and Form 10F included, is what actually gets treaty benefits accepted rather than challenged.
We regularly advise NRIs, OCI holders, returning Indians, US citizens living in India, Green Card holders, foreign nationals working in India, expatriates, startup founders, foreign investors, PE and VC funds, global executives, family offices, multinational companies, Indian businesses earning overseas income, and foreign companies operating in India.
If you receive a foreign salary, hold overseas investments, earn royalty or interest income, own assets abroad, or operate a cross-border business, working with experienced DTAA consultants in India can help you understand your treaty position, avoid unnecessary double taxation, manage withholding requirements, and claim eligible tax relief.
Whether you're an individual with international income or a business with cross-border operations, the right DTAA advice can make a meaningful difference to your overall tax liability, compliance requirements, and the amount you ultimately retain.
Income taxed in one country is exempt in the other, under the specific treaty provisions. This generally applies where the treaty gives exclusive taxing rights to one jurisdiction certain employment income, pensions, or business profits, depending on the treaty. It's the simpler outcome: eliminates the double tax entirely and cuts down the compliance burden.
The more commonly used mechanism under India's treaties. Income can be taxable in both countries, but your country of residence generally credits you for tax already paid at source. So an NRI in the US earning Indian rental income gets taxed in India, reports the same income in the US, and can generally claim a Foreign Tax Credit there for the Indian tax already paid, subject to US rules and the treaty.
Property sales are one of the most common cross-border transactions NRIs deal with, and capital gains here can sit under both the Indian Income Tax Act and the applicable DTAA at the same time.
Under most of India's treaties, gains from selling immovable property in India are taxable in India regardless of where the seller lives. Your country of residence may tax the same gain too but relief is generally available through the DTAA via a Foreign Tax Credit.
Our advisory here covers residential status analysis, capital gains computation, DTAA applicability, Lower/Nil TDS Certificate advisory, Foreign Tax Credit planning, Form 10F assistance, TRC advisory, repatriation planning, and FEMA compliance. A US-based taxpayer selling a flat in India, for example, pays capital gains tax in India and may need to report the same gain in the US with the Indian tax generally claimable as a US Foreign Tax Credit, subject to the treaty and domestic rules. Planning this before the sale, not after, is what actually reduces the total exposure.
NRIs and overseas investors commonly earn dividends from Indian listed companies, private companies, and broader investment portfolios. How that dividend gets taxed depends on your country of residence, the applicable DTAA, domestic tax rules, treaty conditions, and beneficial ownership requirements.
| Country | Indicative Treaty Rate* |
|---|---|
| United States | 15% |
| United Kingdom | 10% |
| Canada | 15% |
| Singapore | 10% |
| UAE | Treaty specific |
*Actual treatment depends on the specific treaty article, beneficial ownership conditions, and applicable domestic law worth confirming the current rate before relying on this table.
We handle dividend withholding tax review, treaty eligibility analysis, Form 10F assistance, TRC advisory, Foreign Tax Credit planning, cross-border dividend structuring, and the documentation to support proper planning here is what keeps withholding from eating into your actual post-tax return.
Interest income is one of the more commonly misunderstood categories in cross-border tax. Depending on the source and the treaty, reduced withholding rates may apply covering bank deposits (NRO interest, resident savings accounts, fixed deposits, corporate deposits), debt investments (bonds, government securities, corporate debt, foreign bonds), and financing arrangements (ECBs, shareholder loans, inter-company financing).
The applicable treaty typically caps the withholding rate, subject to its own conditions. We handle the treaty analysis, interest withholding review, Foreign Tax Credit planning, documentation, Form 10F, TRC support, and structuring for cross-border financing arrangements.
Royalty and Fees for Technical Services are among the most disputed areas in international tax get the characterization wrong and it can materially change your withholding obligation and total liability.
Royalty generally covers payments for using intellectual property or similar rights copyrights, software licenses, patents, trademarks, designs, know-how, industrial equipment, and technology licenses though the exact definition shifts from treaty to treaty.
Fees for Technical Services generally covers payments for technical, consultancy, or managerial services, with the actual tax treatment depending on domestic law, the applicable DTAA, the nature of the service, and the specific treaty provisions.
Several Indian treaties the India-USA and India-UK DTAAs especially include a Make Available clause. Under this, technical services are only taxable where the provider actually makes available the underlying knowledge, experience, or skill in a way that lets the recipient apply it independently afterward. This shows up constantly in consulting, engineering, technical advisory, software implementation, and business advisory work.
| Country | Make Available Clause |
|---|---|
| USA | Yes |
| UK | Yes |
| Canada | Limited application |
| Singapore | Treaty specific |
| UAE | Treaty specific |
We handle royalty characterization, FTS analysis, treaty interpretation, Make Available review, withholding tax planning, cross-border contract review, and PE analysis alongside all of this.
Business profits are generally only taxable in India if a foreign enterprise has a Permanent Establishment here whether that's true depends on a fixed place of business, employees working in India, how long activities run, dependent agents, and the nature of the services provided. Get this analysis wrong and the tax exposure can be significant.
Fixed Place PE a branch office, office, factory, workshop, or warehouse.
Service PE employees or personnel providing services in India beyond the treaty's prescribed duration.
Agency PE a dependent agent habitually concluding contracts on the foreign enterprise's behalf.
Construction PE construction projects running longer than the treaty's threshold.
We handle PE risk assessment, cross-border contract review, employee secondment planning, remote-work implications, digital business PE analysis, BEPS considerations, OECD guidance, and treaty interpretation across all of these.
To claim treaty benefits successfully, you'll want: PAN, passport, Tax Residency Certificate, Form 10F, a self-declaration, passport and visa copies, overseas address proof, your foreign Tax Identification Number, income documents, bank statements, dividend statements, interest certificates, property sale documents, capital gains computation, foreign tax payment proofs, tax returns, Form 16A or TDS certificates, and a DTAA declaration where required. Having this complete and ready reduces the risk of a treaty claim being challenged or denied during assessment.
A Tax Residency Certificate alone often isn't enough to claim DTAA benefits in India where the TRC doesn't contain everything required, eligible non-residents generally need to also furnish Form 10F.
Under the 1961 Act, this ran through Form 10F. Under the 2025 Act, the same requirement has been renumbered Form 41, serving the identical purpose. It's generally filed electronically through the Income Tax Portal.
Our DTAA advisory here covers eligibility determination, TRC review, preparing and filing Form 10F (Form 41 under the 2025 Act), PAN applicability review, digital filing support, Income Tax Portal assistance, documentation verification, resolving filing errors, treaty documentation support, and planning around lower withholding. Filing this on time is what actually protects the reduced withholding rate miss it and treaty benefits can get denied on a purely procedural basis.
| Income-tax Act, 1961 | Income-tax Act, 2025 | Purpose |
|---|---|---|
| Form 10F | Form 41 | Furnishing prescribed information to claim DTAA benefits where the TRC doesn't contain all required particulars |
A TRC is issued by the tax authority of the country where you're actually considered a tax resident, and it's one of the core documents needed to claim DTAA benefits in India. We help determine TRC requirements, review documentation, provide country-specific residency guidance, coordinate with overseas tax professionals where needed, support the Form 10F filing, and handle the broader treaty documentation and withholding tax planning.
Where income is taxable in both India and another country, you can generally claim relief via Foreign Tax Credit, subject to domestic law and the applicable treaty relevant across salary, rental, dividend, interest, capital gains, business, professional, royalty, and FTS income.
Our FTC advisory covers DTAA analysis, the FTC computation itself, documentation review, Indian tax credit planning, overseas tax credit planning, Form 67 advisory for Indian claims, country-specific planning, and broader cross-border optimization, the goal being that tax paid abroad actually gets used efficiently rather than sitting unclaimed.
Applying a DTAA is never just "find the right treaty" it takes analyzing tax residency, the nature of the income, treaty provisions, domestic law on both sides, withholding obligations, and the reporting requirements in each jurisdiction, all at once.
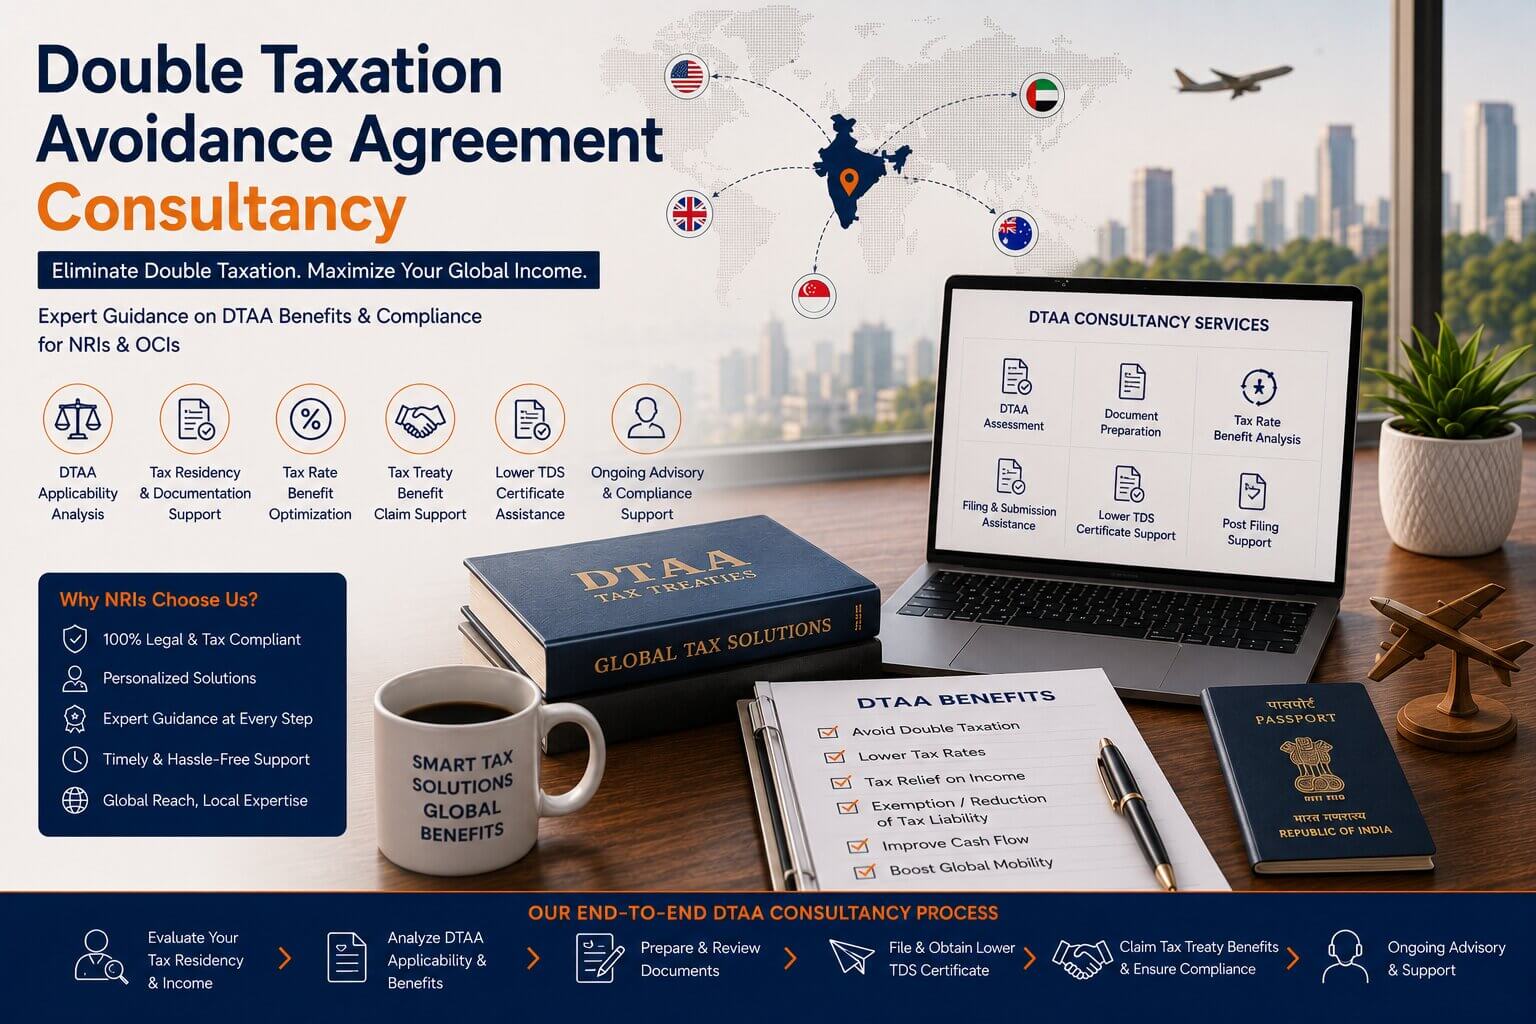
We provide end-to-end DTAA advisory for NRIs, OCI holders, expatriates, multinationals, foreign investors, startups, high-net-worth individuals, and globally mobile professionals, covering:
India's 90-plus treaties are genuinely not interchangeable residency definitions, PE thresholds, royalty and FTS treatment, capital gains rules, dividend and interest rates, and FTC mechanics all differ by treaty.
India-USA DTAA one of the more comprehensive treaties, covering Foreign Tax Credits, Form 1116 planning, pension taxation, Social Security, capital gains, royalty, the Make Available clause, FTS, business profits, PE, and Form 8833 support. Most relevant for US citizens, Green Card holders, H-1B professionals, NRIs returning from the US, and US companies investing in India.
India-UK DTAA covers UK salary income, pension taxation, rental income, dividend taxation, capital gains, royalty, the Make Available clause, Foreign Tax Credits, and TRC/Form 10F work.
India-Canada DTAA covers RRSP taxation, Canadian pensions, rental income, Foreign Tax Credits, investment income, cross-border residency, and capital gains planning.
India-UAE DTAA covers tax residency, salary income, business profits, dividend taxation, property income, family office structures, investment planning, and cross-border remittances.
India-Singapore DTAA covers holding companies, investment funds, startup investments, capital gains, dividend taxation, treaty benefits, and Foreign Tax Credits.
India-Australia DTAA covers employment income, superannuation, capital gains, Foreign Tax Credits, investment income, and cross-border tax residency.
India-Germany DTAA covers business profits, PE, royalty, FTS, technical consulting, engineering projects, and cross-border employment.
International tax planning takes more than reading the treaty text; it takes real experience applying treaty provisions alongside domestic tax law, FEMA, withholding rules, foreign tax credit mechanics, and cross-border structuring, all at once.
Twenty-five-plus years in this practice, more than 10,500 NRI and international tax clients served, and a team built specifically around this Chartered Accountants, US CPAs, Enrolled Agents, and ACCAs with real depth in the India-USA, India-UK, India-Canada, India-UAE, and India-Singapore treaties, plus Form 10F/Form 41, TRC, and Foreign Tax Credit work specifically. We work across income tax, FEMA, RBI, GST, and international taxation as one integrated service, with a secure digital process and year-round support rather than a once-a-year engagement.
You're a resident of India if your stay in a given financial year is 182 days or more, or 60 days or more combined with 365 days or more across the four preceding years. If neither condition is met, you're an NRI.
Once your gross total income received in India exceeds Rs 2.5 lakh in a financial year, filing is required generally due July 31 of the assessment year, unless extended by the government.
Depends on your residential status for the year. If you're "resident," your global income is taxable in India. If you're "NRI," only income earned or accrued in India is taxable salary for services rendered in India, income from Indian house property, capital gains on Indian assets, and interest on fixed deposits or savings accounts all count. Income earned entirely outside India isn't taxable here. NRE and FCNR account interest stays tax-free; NRO account interest is taxable in an NRI's hands.
No it applies to anyone earning income in India, resident or not.
Residents are taxed on global income in India. Non-residents are taxed only on income earned in India or sourced from an Indian activity.
Yes, if your expected tax liability for the year exceeds Rs 10,000 missing it brings interest under Sections 234B and 234C.
It is worth checking whether your destination country has a DTAA with India. These arrangements exist specifically so the same income doesn't get taxed twice once you're earning in one country and potentially liable in both.
Yes, following the amendment passed by Parliament in February 2020, dividend income earned by a non-resident from an Indian company is taxable in India. The applicable rate is whichever is more favourable between the DTAA rate and the Income Tax Act rate generally somewhere in the 5–10% range for NRIs, depending on the specific treaty.
FCA, B.Com (H)
FCA, ACCA, B. Com (H)
MBA (Int'l Banking & Finance), LLB, B. Com (H)
ACA, CISA, B. Com (H)
FCA, B.Com (H)
FCA, B.Com (H)

CPA(USA), FCA, CISA, B.Com (H)
EA, CA, M.Com, B.Com (H)
CPA, FCA, B. Com (H)
CA, B.Com
FCA, B.Com (H)

FCA, ACCA, B. Com (H)
MBA (Int'l Banking & Finance), LLB, B. Com (H)
ACA, CISA, B. Com (H)
FCA, B.Com (H)
FCA, B.Com (H)
CPA(USA), FCA, CISA, B.Com (H)
EA, CA, M.Com, B.Com (H)
CPA, FCA, B. Com (H)
With over 21 years of experience, Mr. Abhishek Batra specializes in NRI taxation and cross-border corporate tax strategies. His expertise spans tax planning, compliance advisory, and financial structuring, helping individuals and businesses navigate complex international tax regulations.
Based in Canada, Mr. Batra offers tailored solutions to NRIs, expatriates, and global companies with operations in India. A Chartered Accountant, CPA, and SRCC graduate, he is known for delivering impactful financial strategies that support growth and compliance.
CA, B.Com
An Experienced Chartered Accountant with over 5 years of expertise in cross-border taxation, NRI taxation, and US tax compliances. She has extensive exposure in handling complex international tax matters, including India-US taxation, DTAA advisory, foreign disclosures, expatriate taxation, and tax planning for NRIs and returning Indians.
She is a Chartered Accountant and a Commerce Graduate, with strong proficiency in US tax filings and global tax advisory services.
.webp)


