WhatsApp
 Call Us
 Email Us
 Whatsapp Community

Would you like to schedule a call back
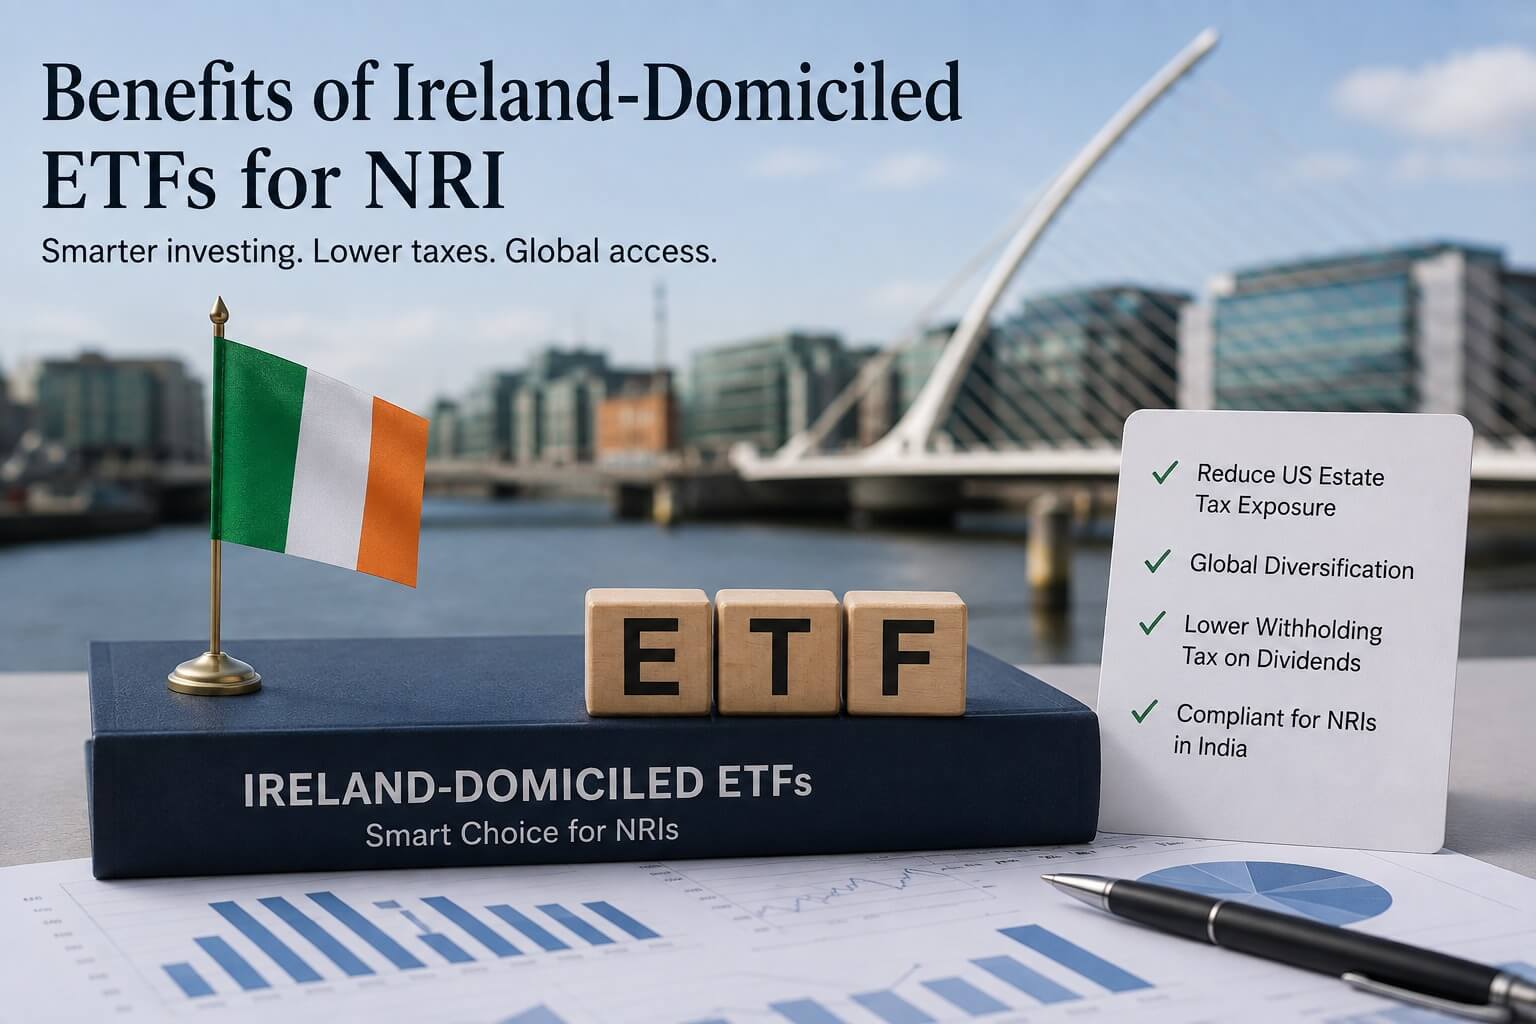


If you're a returning NRI who isn't a US citizen or green card holder, Ireland-domiciled ETFs solve a specific and expensive problem: they take your US equity holdings out of the US estate tax net entirely. Once you give up US domicile, the exemption on your US-situs assets falls from the citizen-level $15 million to just $60,000, with tax running up to 40% above that and the India-US tax treaty gives you no protection here, because no estate tax treaty between the two countries exists. An Ireland-domiciled UCITS fund holding the same Apple or Microsoft shares you already own isn't a US-situs asset, so that exposure simply doesn't arise. This is the single fact that makes the structure worth understanding before you file your first return as an Indian resident.
Ireland-domiciled ETFs are funds legally organised in Ireland under the UCITS framework (Undertakings for Collective Investment in Transferable Securities), a European fund structure regulated by the Central Bank of Ireland with strict diversification and investor-protection rules. What confuses most first-time investors is that these funds often hold nothing but US stock the fund tracks the S&P 500 or a global equity index, and the underlying companies are the same American names you'd hold through a US-listed ETF. The difference that matters is not what the fund owns, it's where the fund itself is domiciled.
The most common Ireland-domiciled equivalents are CSPX (tracking the S&P 500), IWDA (developed-market equity), and VWCE (all-world equity). They trade on the London Stock Exchange and Deutsche Börse's Xetra, not on the NYSE or Nasdaq VOO and SPY, by contrast, are US-domiciled and don't carry any of the advantages discussed below.
While you're a US resident, the IRS treats you as domiciled there, so your estate gets the same exemption a citizen gets $15 million in 2026. The moment you move back to India and give up that domicile, if you're not a US citizen or green card holder, the exemption on your US-situs assets collapses to $60,000. That number hasn't moved in decades and isn't indexed to inflation. Everything above it is taxed on a schedule that reaches 40%, and the estate must file Form 706-NA before US probate releases the assets to your heirs.
US-situs assets include US stocks, US-domiciled ETFs, and US brokerage holdings, and they remain US-situs even inside an account you opened while you were a US resident. The example below shows what this looks like on a straightforward equity holding:
|
What happens on the estate |
Amount |
|
US-situs holding (US stocks/ETFs) |
$500,000 |
|
Less: non-resident exemption |
$60,000 |
|
Taxable estate |
$440,000 |
|
Estate tax at up to 40% |
≈ $176,000 |
In our advisory conversationgs with returning NRIs, the most common and costly misread is assumin the India-US DTAA covers this. It doesn't there is no US-India estate tax treaty, and the income-tax DTAA has no estate tax article at all. The $60,000 exposure is real, and it applies regardless of what the treaty covers on the income-tax side.
For estate tax purposes, only the fund's domicile matters not what it holds. Because a UCITS fund is legally organised outside the US, its units aren't US-situs property, even when the fund is fully invested in US equities. That single structural fact removes the holding from the $60,000 problem completely.
Ireland itself doesn't tax a non-resident investor: no Irish capital gains tax, no Irish dividend withholding at your level, and no Irish estate or inheritance tax, provided you (or your broker) has the standard non-residency declaration on file. The underlying tax doesn't disappear it simply shifts to wherever you're actually resident, which for a returning NRI means it lands in India under Indian rules, not in the US estate tax regime.
When NRIs return to India, they can typically claim RNOR (Resident but Not Ordinarily Resident) status for up to three financial years. During this window, you're treated as an Indian resident for FEMA purposes but as a non-resident for Indian tax on foreign income and foreign capital gains.
There's a second, less-discussed use of this window: if a holding is sitting on a gain late in your RNOR period, selling and rebuying resets your cost basis to the current, higher price tax-free, since you're still outside the Indian capital gains net. That higher basis lowers the Indian capital gains tax you'll eventually owe once you're a full resident and do have to pay tax on the gain. It's a one-time opportunity that closes the day your RNOR status ends, so it's worth checking your holdings against it before that window shuts.
Once your RNOR period ends, you become a Resident and Ordinarily Resident (ROR), and Indian income tax applies fully to your global income and capital gains, including these ETF holdings.
|
Holding period |
Tax treatment |
|
Held more than 24 months |
Long-Term Capital Gains (LTCG) at 12.5%, without indexation |
|
Sold within 24 months |
Short-Term Capital Gains (STCG), taxed at your applicable income tax slab rate |
Even after RNOR ends, Ireland-domiciled ETFs continue to offer the same global diversification and freedom from US estate tax risk the only change is that Indian tax now applies to the gains, the same way it would on any foreign security.
The estate tax advantage is the headline reason to prefer the Irish wrapper, but there's a second, recurring advantage that shows up every year rather than only at death how dividends are taxed before they ever reach you.
|
What happens |
US stock / US-domiciled ETF |
Ireland-domiciled UCITS ETF |
|
US estate tax |
Exposed above $60,000, up to 40% |
Not a US-situs asset — no exposure |
|
Dividend withholding at source |
25% with a valid W-8BEN, 30% without |
15% at fund level, under the US-Ireland tax treaty |
|
Irish tax for a non-resident |
Not applicable |
None, with the non-residency declaration on file |
|
Interim dividend tax event in India |
Yes, when the dividend is paid |
None, if you hold an accumulating share class |
That 15% is withheld at the fund level under the US-Ireland treaty, before the fund even values its units, so it never appears as a line item on your statement. Choose an accumulating share class over a distributing one, and the fund reinvests the dividend automatically which means no cash reaches you and no Indian dividend-tax event is triggered that year.
This entire approach depends on one condition: you are not a US citizen and you do not hold a US green card. If either applies to you, an Ireland-domiciled fund creates a different and considerably worse problem than the one it solves.
For a US person, an Ireland-domiciled UCITS ETF is classified as a PFIC (Passive Foreign Investment Company). That triggers punitive tax treatment and a Form 8621 filing requirement for every fund, every year rules that have nothing to do with estate tax and that can erase any benefit the structure was meant to deliver. If you're still a US person for tax purposes, this route isn't for you until that status changes.
It's also worth weighing GIFT City as a domestic alternative before going offshore. India's GIFT City offers dollar-denominated investment routes through Indian institutions, giving you US-dollar exposure without moving money to a foreign broker at all a reasonable fit if you'd rather avoid foreign-account paperwork and don't have the same estate tax exposure to begin with.
The most common question we get on this topic is simply how to invest legally and efficiently from India. Here's the route that works in practice:
Under FEMA Section 6(4), NRIs returning to India are permitted to continue holding foreign assets that were acquired while they were non-residents this includes foreign bank accounts, foreign stocks and ETFs, and real estate held outside India. During your RNOR window, there's no obligation to bring these funds back to India, and no requirement to report them in your Indian tax return.
Once RNOR ends and you're a full resident, these holdings must be disclosed under Schedule FA (Foreign Assets) in your Indian income tax return, and gains are taxed as foreign securities under the LTCG/STCG rules above. That disclosure isn't optional skipping it carries its own penalty under Indian law, entirely separate from the tax due on the gain itself, so it's worth treating as a compliance item on its own rather than an afterthought to the capital gains calculation.
|
Criteria |
US Stock / US-Domiciled ETF |
Ireland-Domiciled ETF (RNOR) |
Ireland-Domiciled ETF (ROR) |
|
US estate tax risk |
Exposed above $60,000, up to 40% |
None — not US-situs |
None — not US-situs |
|
Tax on gains in India |
N/A during RNOR / taxable as ROR |
Not taxable in India |
LTCG 12.5% (>24 months) or slab-rate STCG |
|
Foreign asset reporting |
N/A |
Not required |
Mandatory under Schedule FA |
|
Dividend withholding |
25–30% |
15% at fund level |
15% at fund level |
|
Recommended route |
— |
IBKR/Paasa, funded from US account |
Same, or LRS post-residency |
At Dinesh Aarjav & Associates, we help NRIs, OCIs, and expatriates navigate the transition to India with RNOR tax strategy, global portfolio restructuring, foreign asset compliance, and FEMA and LRS advisory. With over 25 years of experience and clients across the US, UK, UAE, Australia, and Canada, we provide tailored NRI advisory services designed to ensure full compliance and wealth preservation.
Contact us today to discuss your RNOR phase, foreign investments, and cross-border NRI tax planning.
CA Priyal Goel Jain is a Partner at Dinesh Aarjav & Associates and a leading expert in India–US cross-border taxation, NRI taxation, and international tax advisory. She advises NRIs, OCIs, and global families on complex cross-border transactions, tax planning, foreign asset reporting, and multi-jurisdictional compliance matters.

Stay in the loop, subscribe to our newsletter and unlock a world of exclusive updates, insights, and offers delivered straight to your inbox.
.webp)