WhatsApp
 Call Us
 Email Us
 Whatsapp Community

Would you like to schedule a call back
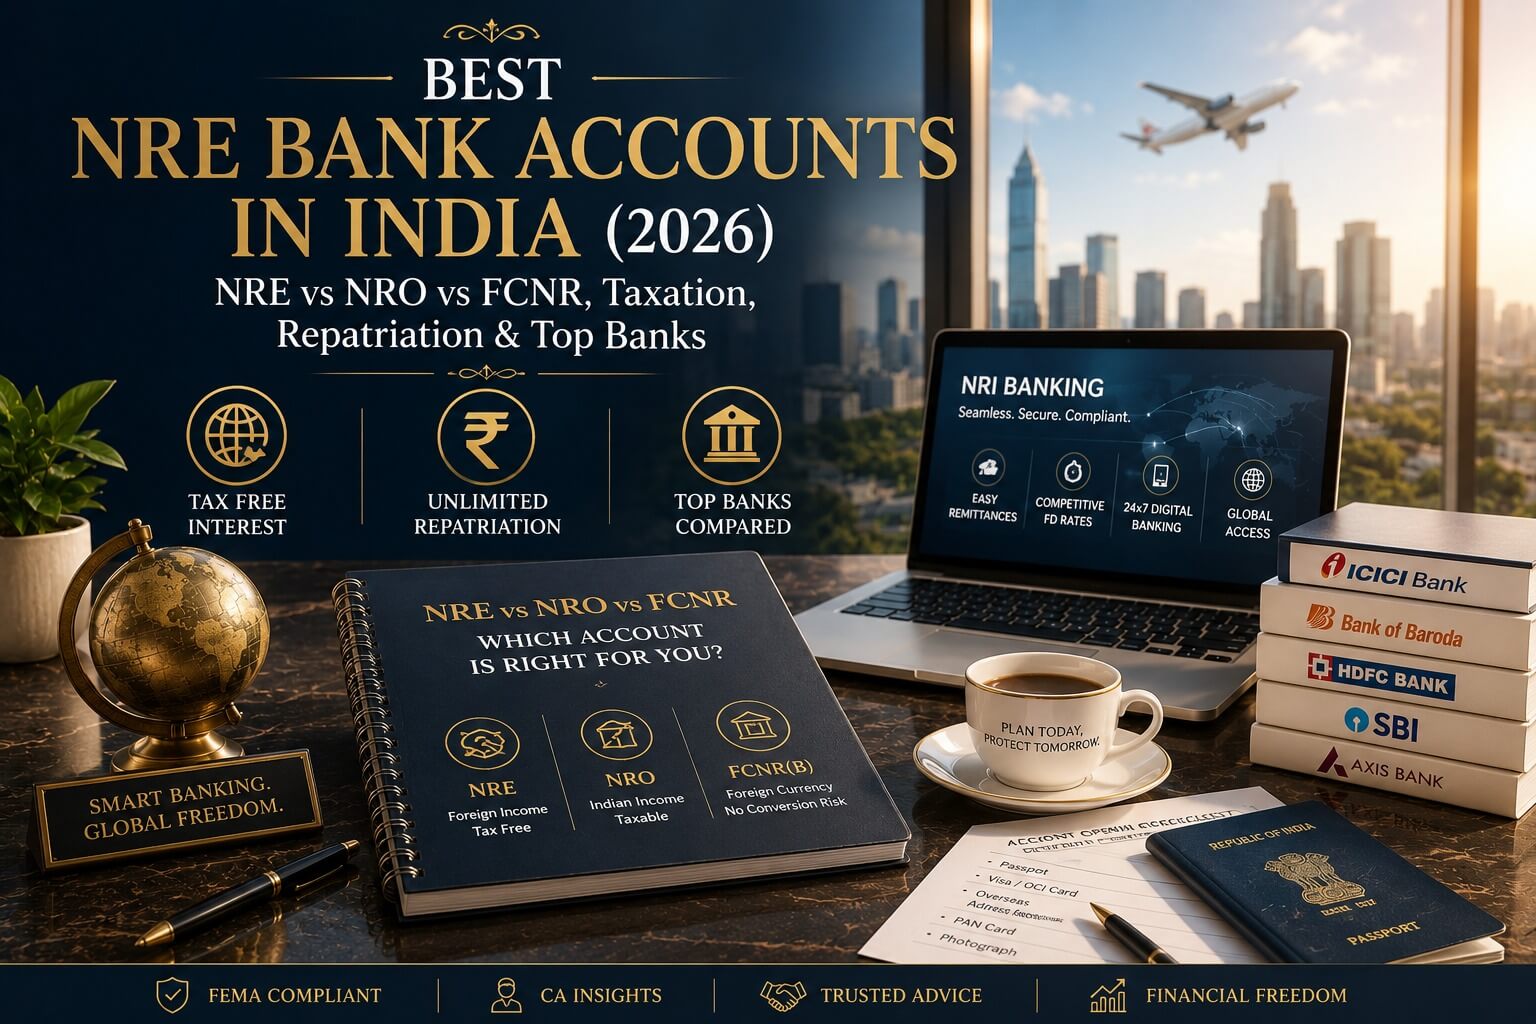


If you're an NRI figuring out your banking options in India, the first question is rarely which bank to pick. It's usually whether you can keep the savings account you've had since college. The short answer: you can't. The moment your residential status changes, FEMA requires you to move out of a resident savings account. Your options are an NRE account, an NRO account, or an FCNR(B) deposit, and each one comes with different tax and repatriation rules.
Choosing the right account early saves a lot of paperwork down the line. This guide explains what each account does, how they're taxed, which banks are worth considering for NRI banking in India in 2026, and what documents you'll need to get started.
An NRE (Non-Resident External) account is a rupee-denominated account for money you earn outside India. You deposit in foreign currency, it converts to INR at the prevailing exchange rate, and you withdraw in rupees.
NRE account benefits include:
This is the most popular choice for NRIs whose income is entirely foreign-sourced and who want the flexibility to move money in and out of India without restrictions.
An NRO (Non-Resident Ordinary) account is designed for income you earn inside India, things like rent, dividends, a pension, or interest on Indian deposits.
Key features to know:
If you have ongoing Indian income streams, an NRO account is the compliant place to receive and hold that money.
An FCNR(B) (Foreign Currency Non-Resident Bank) account is a term deposit held in a foreign currency such as US dollars, British pounds, or euros. It never converts to rupees, which makes it the right fit for NRIs who don't want currency conversion risk on their savings.
Here's what sets it apart:
The practical upside: if the rupee weakens between now and your deposit's maturity, an FCNR deposit is unaffected. An NRE deposit converted to INR today could buy back fewer dollars at maturity.
| Feature | NRE Account | NRO Account | FCNR(B) Deposit |
|---|---|---|---|
| Source of funds | Foreign income | Indian income | Foreign income |
| Currency held in | INR | INR (forex deposits accepted) | Foreign currency, no conversion |
| Taxation in India | Tax-free interest | Taxable, TDS applies | Tax-free interest |
| Repatriation | Unlimited | Up to USD 1 million per FY | Unlimited |
| Currency risk | Yes, rupee conversion applies | Not applicable | None |
| Joint holder | Another NRI only | NRI or resident Indian relative | Another NRI only |
A simple way to think about it: if your income is foreign and you're comfortable with rupee conversion, go with an NRE account. If you want to avoid rupee volatility entirely, an FCNR deposit is the better fit. If you have Indian income to manage, you need an NRO account. Most NRIs end up holding at least two of these.
Picking the right bank for your NRI banking in India comes down to a few practical factors: how fast remittances clear, how good the mobile app is, what NRE FD rates 2026 look like for the tenures you want, and whether your family in India has easy branch access.
Here are the banks that come up most often, and why.
ICICI is the most consistently recommended NRE bank account option for NRIs based in the US, UK, and UAE. The mobile app is strong, remittance processing is fast, and the NRE fixed deposit options cover a wide range of tenures. If your priority is a smooth digital experience from abroad, this is the natural starting point.
Bank of Baroda tends to sit toward the top when you compare NRE account interest rates, with the added reassurance of a public-sector bank. It also has a wide branch network, which helps if your family in India needs in-person support.
SBI runs the largest branch network of any Indian bank, plus a dedicated Global NRI Centre. For NRIs whose families rely on physical branch access, or who want a bank with a genuinely deep correspondent network for international remittances, SBI is hard to match on pure reach.
Axis offers a clear set of account tiers, from a basic NRI savings account up to the relationship-manager-backed Burgundy tier. It also has a fully digital route to open US-dollar fixed deposits through its GIFT City IFSC Banking Unit, which is useful if you want a foreign-currency deposit without travelling to India.
IDFC First has built its NRI offering around cost and currency flexibility. Its app includes a zero-fee remittance platform, and its GIFT City-based Global Savings Account lets you hold USD or EUR directly. FCNR deposits are also available in USD, EUR, GBP, SGD, and AUD. If remittance costs matter more to you than branch access, this one is worth a close look.
HDFC Bank, Federal Bank, Kotak Mahindra Bank, and DBS Bank all run solid NRE, NRO, and FCNR programmes. Federal Bank and South Indian Bank have historically offered aggressive NRE deposit rates to attract Gulf-based NRIs specifically.
One note of caution: NRE FD rates 2026 shift often, sometimes within weeks of what a bank has published. Treat any rate comparison, including this one, as a starting shortlist. Always confirm the current NRE account interest rates directly on the bank's NRI page or with their NRI relationship desk before committing to a deposit.
The tax treatment is one of the most important things to get right.
NRE accounts and FCNR deposits both offer fully tax-exempt interest in India. No TDS is deducted, and both principal and interest can be repatriated freely at any time. This is a big part of why NRE FDs are a popular tax-efficient option for foreign savings.
NRO accounts are taxed differently. Interest is fully taxable and TDS is deducted at source. Repatriating funds requires Form 15CA and, above the prescribed threshold, a CA-certified Form 15CB. Annual repatriation is capped at USD 1 million.
Continuing to use a resident savings account after your status changes to NRI is a FEMA violation, not just an administrative oversight. The consequences are real:
The fix is simple. As soon as your status changes, ask your bank to convert the resident account to an NRO account, or close it and open a fresh NRE or NRO account. Most major banks handle this conversion without requiring you to be physically present in India.
Getting your paperwork together upfront makes the process much smoother. You'll typically need:
Most major banks now support video-KYC or fully online account opening for NRIs, so a trip to India is not usually necessary.
A few of these come up again and again, and they're all avoidable.
Most NRIs are better served by holding more than one account rather than picking a single winner, because each account solves a different problem.
| Your situation | What to open |
|---|---|
| Foreign income, want digital convenience | NRE account at ICICI Bank |
| Foreign income, want best NRE FD rates | NRE account at Bank of Baroda |
| Family needs local branch access | NRE account at SBI |
| Want tiered service and GIFT City deposits | NRE account at Axis Bank |
| Want zero-fee remittances, multi-currency flexibility | NRE or FCNR at IDFC First Bank |
| Worried about rupee volatility | FCNR(B) deposit instead of NRE |
| Have both foreign and Indian income | Open NRE plus NRO (add FCNR if rate and currency flexibility matter) |
If you need help choosing the right accounts, comparing current NRE FD rates 2026 across banks, or handling Form 15CA/15CB for an NRO repatriation, the NRI services team at Dinesh Aarjav & Associates can walk you through it from start to finish.
CA Disha Bansal is a tax professional at Dinesh Aarjav & Associates specializing in US taxation, India–US cross-border tax advisory, and NRI tax compliance. She advises individuals and NRIs on US tax return preparation, international reporting requirements, cross-border tax planning, and navigating complex India–US tax matters, helping clients manage their global tax obligations efficiently and compliantly.


Stay in the loop, subscribe to our newsletter and unlock a world of exclusive updates, insights, and offers delivered straight to your inbox.
.webp)