WhatsApp
 Call Us
 Email Us
 Whatsapp Community

Would you like to schedule a call back


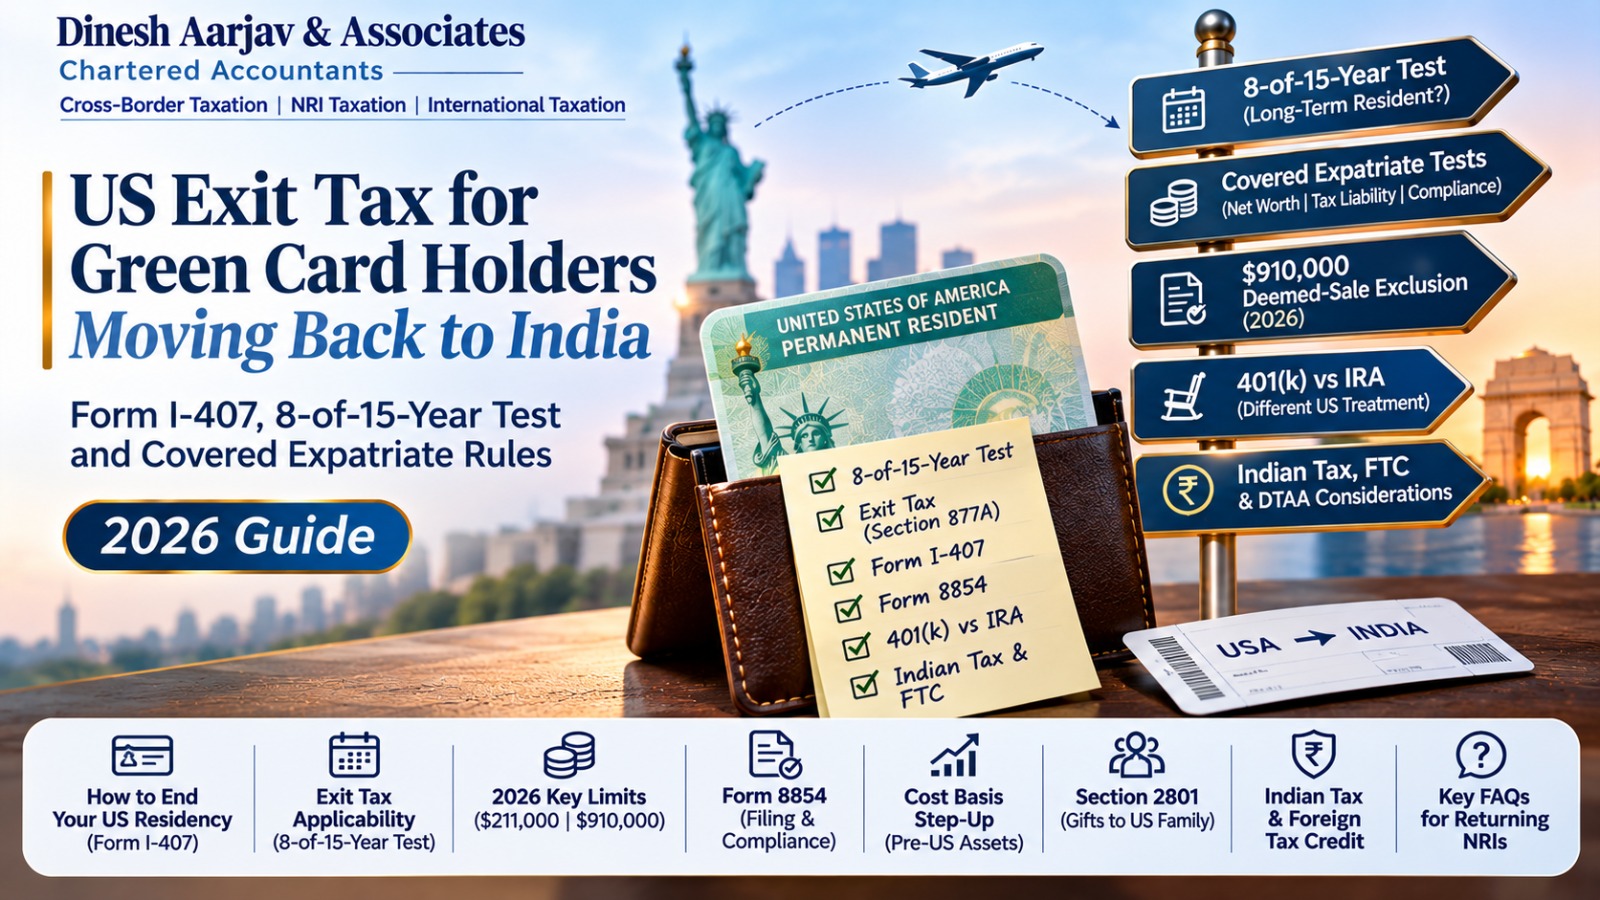


US exit tax for green card holders only applies if you held your card in at least 8 of the last 15 tax years. If you did, you're a "long-term resident," and you then check whether you're a "covered expatriate." Many people returning to India never hit either test, so the exit tax may not apply to you at all.
Here's the quick version, then we'll walk through it step by step.
You're a long-term resident if you held a green card in 8 of the last 15 tax years. Any part of a year counts as a full year.
If you are a long-term resident, you're a covered expatriate when any one of these is true:
Covered expatriates are taxed as if they sold everything the day before giving up the card. The first $910,000 of gain is excluded.
One more thing matters a lot. Moving to India doesn't end your US tax residency. Until you surrender the card (usually with Form I-407), the US still taxes your worldwide income, even while you live in India.
This guide is for Indians who hold a green card, have moved back to India (or plan to), and aren't sure what to do with the card. If that's you, there are two questions to ask. First, can the exit tax apply to me at all? Second, how do I end my US tax residency cleanly?
The second one trips up a lot of people. They leave with the card in a drawer and are still US taxpayers years later without knowing it. If you're a US citizen instead, see our guide to renouncing US citizenship from India.
You're a long-term resident if you held a green card in at least 8 of the 15 tax years ending with the year your residency ends. The exit tax under Section 877A applies only to citizens and long-term residents, so this test comes first.
Two counting rules decide most cases:
Here's how it plays out:
| Green Card Received | Surrendered | Years Counted | Long-Term Resident? |
|---|---|---|---|
| March 2020 | November 2026 | 7 (2020 to 2026) | No, exit tax can't apply |
| December 2019 | January 2026 | 8 (2019 to 2026) | Yes, exit tax tests apply |
| June 2014 | June 2026 | 13 (2014 to 2026) | Yes, exit tax tests apply |
If you're not a long-term resident, there's no exit tax and no Form 8854. You still need to end your residency properly and file a final dual-status return, but the big risk is gone.
If you're close to eight years, the timing of your surrender can decide everything. Giving up the card in December instead of the following January might keep you under the line.
You end it by formally giving up your permanent resident status, most often with Form I-407. Leaving the country doesn't do it. Let's look at why, and what your options are.
No. A green card makes you a US tax resident whether or not you live in the US. Moving to Bengaluru, letting the card expire, or never using it again changes nothing.
Until your status is formally given up or taken away, you must:
An expired card is just an expired document. Your status as a permanent resident continues.
Most people file Form I-407 (Record of Abandonment of Lawful Permanent Resident Status) with US Citizenship and Immigration Services. Follow the current filing instructions on the form.
For tax purposes, your residency generally ends on the date you file. If you're a long-term resident, that date is your expatriation date. Keep the USCIS acknowledgement, because it's your proof for the IRS.
Not ready to decide yet? A re-entry permit (Form I-131) lets you stay outside the US for up to two years without the card being treated as abandoned. You're still a US tax resident during that time, though.
Some green card holders in India try to stop paying US tax by claiming Indian residency under Article 4 of the India-US tax treaty. They file Form 8833 with a non-resident return.
If you're under the 8-year mark, this can be a fair position. If you're a long-term resident, it's a different story. The IRS treats a new claim of treaty residence in another country as ending your long-term residency. That's an expatriation in its own right, so Form 8854 is due and the covered expatriate tests apply.
Plenty of people make this claim just to cut their yearly US tax, with no idea they've set off the exit tax.
Holding A Green Card While Living In India? We'll count your years under the 8-of-15 test, check whether you're still a US tax resident, and plan the date and method of giving up the card. Depending on that date, the exit tax may not apply to you at all. Book a green card exit review.
You're a covered expatriate if you're a long-term resident and meet any one of three tests on your expatriation date. Here they are:
| Test | 2026 Threshold |
|---|---|
| Net worth | $2,000,000 or more, worldwide (not indexed) |
| Average annual net US income tax, 2021 to 2025 | More than $211,000 (Rev. Proc. 2025-32) |
| Certification | Can't certify on Form 8854 that you met every US tax obligation for the last five years |
A few details help here:
The certification test catches more returning Indians than the other two combined. An unfiled Form 8621 for an Indian mutual fund, a missed FBAR, or a missing Form 3520 for a gift or inheritance from family in India can make you covered at any net worth. Fix those years before you surrender the card.
If you're a covered expatriate, the US treats you as if you sold everything the day before you gave up the card. Let's break down the pieces.
Every asset is treated as sold at market value on the day before your expatriation date, and the gain is taxed that year. For 2026, the first $910,000 of net gain is excluded.
You can choose to defer the tax on particular assets until you actually sell them. But you have to give the IRS security, pay interest, and you can't undo the election later.
This is the most valuable rule for returning Indians, and it's often missed. A long-term resident can treat assets owned on the day they first became a US resident as if they cost the market value on that day.
Say you bought a flat in Pune in 2010 and got your green card in 2015. The US deemed-sale gain is measured from the flat's 2015 value, not your 2010 purchase price.
You can skip this rule for individual assets, but most people want it. A solid valuation for the date you became a US resident is worth the effort.
Each type of account has its own rules:
| Account | Treatment For A Covered Expatriate |
|---|---|
| 401(k), 403(b), US pension (if you file Form W-8CE) | Not taxed at expatriation. Every future payment faces 30% US withholding, with no treaty reduction |
| Traditional IRA, Roth IRA, HSA, 529 plan | Treated as fully withdrawn the day before expatriation. The taxable portion is taxed that year, with no 10% early withdrawal penalty |
| EPF, NPS and other non-US plans | Generally treated as received the day before expatriation, at present value, and taxed then |
No. India doesn't recognise the US deemed sale. Giving up a green card isn't a transfer under Indian law, so there's no Indian tax at expatriation and your Indian cost stays the same.
When you later sell, India taxes the actual gain from your original cost. If the US already taxed a deemed gain on your Indian property, getting credit for that US tax in India is uncertain.
That's why selling certain assets before expatriation is sometimes the smarter route. Both countries then tax the same gain in the same year. Our DTAA advisory team models this case by case.
Meera got her green card in 2015 and moved back to Bengaluru in 2025, keeping the card. She files Form I-407 in 2026. Her years run from 2015 to 2026, which is 12, so she's a long-term resident. Her US filings are up to date, including Form 8621.
The day before her expatriation date, she holds:
| Asset | Market Value | Cost For The Deemed Sale | Deemed Gain |
|---|---|---|---|
| US brokerage shares | $700,000 | $300,000 | $400,000 |
| Bengaluru flat (bought 2010 for $80,000, worth $250,000 in 2015) | $500,000 | $250,000 (step-up to 2015 value) | $250,000 |
| 401(k) | $500,000 | n/a | 30% withholding on future payments |
| Roth IRA (contributions $80,000) | $120,000 | n/a | Treated as fully withdrawn, $40,000 of earnings taxable |
| Cash | $200,000 | n/a | n/a |
| Net worth | $2,020,000 | Covered expatriate (just over $2 million) |
Her deemed gains total $650,000, which is under the $910,000 exclusion. So the deemed sale itself costs her nothing.
Without the step-up, the flat's gain would have been $420,000 and her total $820,000. That's still under the exclusion, but with far less room to spare.
Her real costs are the $40,000 of Roth earnings taxed in 2026 and 30% withholding on every 401(k) payment for life. Both come from being just $20,000 over the net worth line. A gift to family before filing Form I-407 would have kept her out of covered status entirely.
Close To The $2 Million Line Or The Eight-Year Mark? Small moves made before you surrender the card, like timing, a gift or a sale, can decide whether the exit tax applies at all. Get your exit plan modelled.
Giving up the card doesn't cut every US tie. A few things stay with you:
Here's your checklist for the final year:
The biggest one is leaving the US with the card and assuming US tax duties have stopped. They haven't, and those unfiled years then cause trouble with the certification test.
Others we see often:
The cost of giving up a green card depends mostly on when and how you do it. Dinesh Aarjav & Associates prepares US and Indian returns for returning Indians together, so your US exit and your Indian residential status are planned as one.
Our green card exit review covers:
Book your green card exit review or message us on WhatsApp. Also see our US tax return services for NRIs and our guide to returning to India.
*This article is for general information and reflects the law as of November 2026. It is not tax or immigration advice for your specific situation.*
CA Sanyam Goel, CPA (USA), FCA, and CISA, specializes in India–US cross-border taxation, NRI tax advisory, US tax compliance, transfer pricing, and international regulatory matters. He assists clients with US and Indian tax obligations, cross-border reporting requirements, and strategic tax planning for global investments and transactions.
Stay in the loop, subscribe to our newsletter and unlock a world of exclusive updates, insights, and offers delivered straight to your inbox.
.webp)