 WhatsApp
 Call Us
 Email Us
 Whatsapp Community

Would you like to schedule a call back
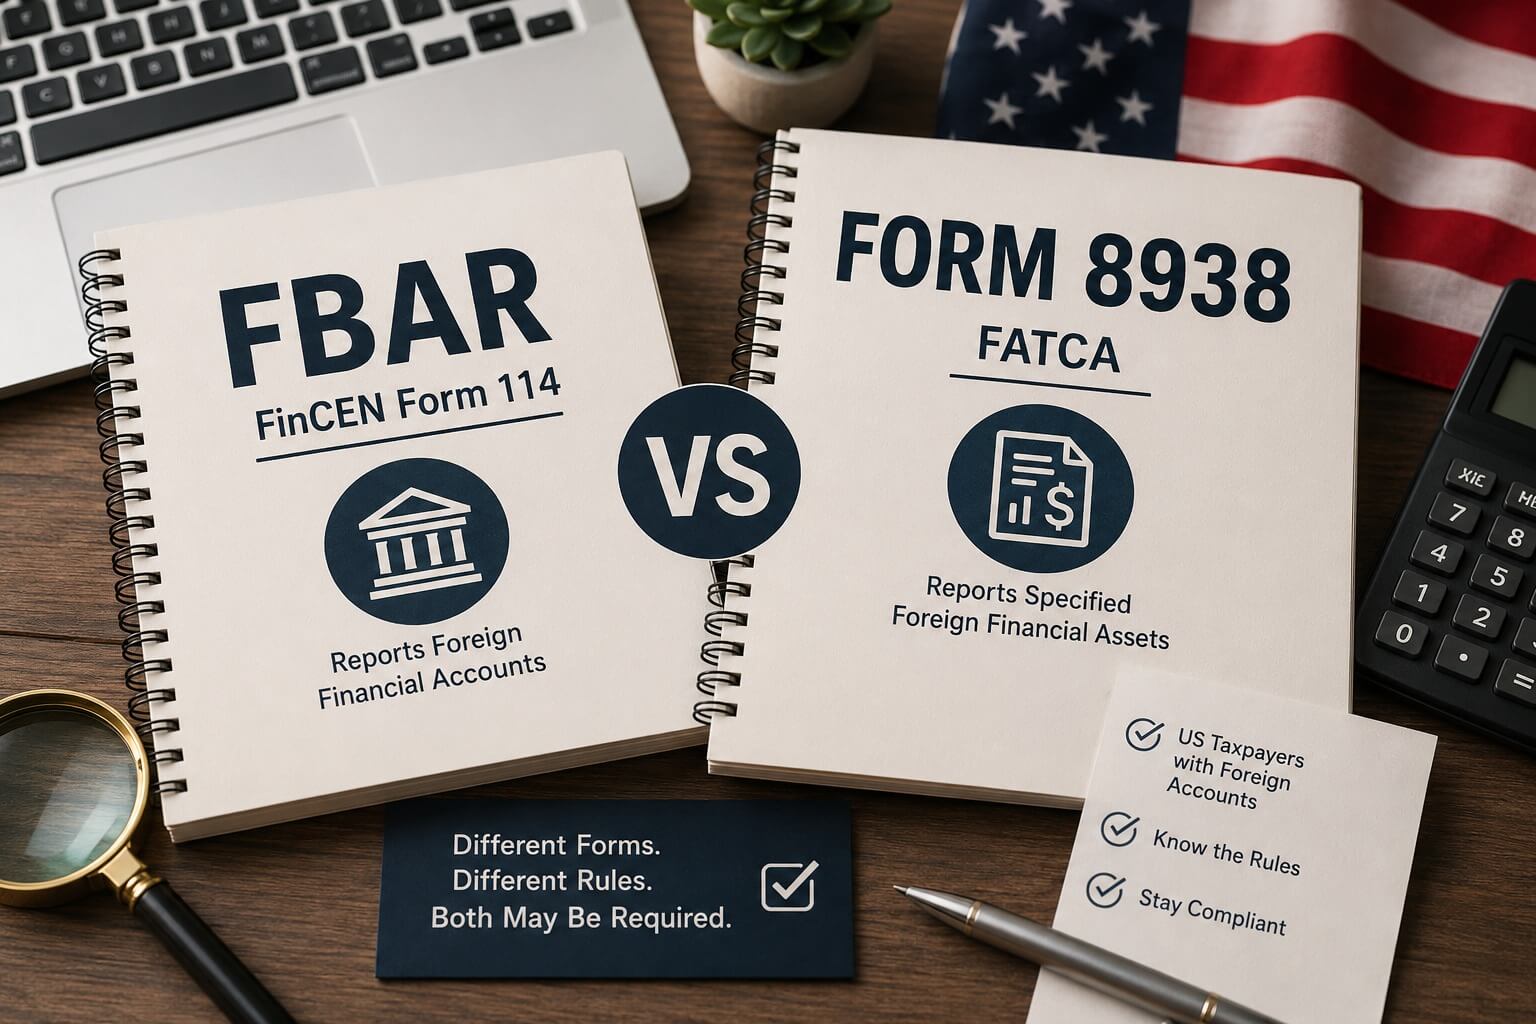


If you are a US citizen, Green Card holder, H-1B professional, or any other US tax resident with bank accounts or investments outside the United States, you have probably come across two important reporting requirements FBAR (FinCEN Form 114) and IRS Form 8938 under FATCA.
Many taxpayers assume these are the same form. They are not.
Although both require reporting foreign financial assets, they are governed by different laws, filed with different government agencies, have different reporting thresholds, and carry separate penalties for non-compliance.
For individuals living in India or maintaining financial assets in India while remaining subject to US taxation, understanding these reporting obligations is essential.
This guide explains everything you need to know about FBAR vs Form 8938, including reporting thresholds, Indian assets that may need disclosure, common mistakes, penalties, and practical examples
|
FBAR |
Form 8938 |
|
Filed with FinCEN |
Filed with IRS |
|
FinCEN Form 114 |
IRS Form 8938 |
|
Reports foreign financial accounts |
Reports specified foreign financial assets |
|
Separate electronic filing |
Filed with your federal tax return |
|
Threshold generally starts at $10,000 aggregate |
Threshold varies based on filing status and residence |
|
Required under Bank Secrecy Act |
Required under FATCA |
Important: Filing Form 8938 does not eliminate the requirement to file FBAR. Many taxpayers are required to file both.
FBAR stands for Foreign Bank Account Report and is filed electronically as FinCEN Form 114.
Its purpose is to help combat tax evasion and financial crimes involving foreign financial accounts.
FBAR is not filed with the IRS. Instead, it is submitted electronically to the US Department of the Treasury’s Financial Crimes Enforcement Network (FinCEN).
You may need to file FBAR if the aggregate highest balance of all your foreign financial accounts exceeded USD 10,000 at any time during the calendar year.
The $10,000 threshold applies to the combined value of all foreign accounts not each account individually.
Form 8938 was introduced under the Foreign Account Tax Compliance Act (FATCA).
Unlike FBAR, Form 8938 is filed along with your annual US income tax return (typically Form 1040).
Instead of focusing only on bank accounts, Form 8938 reports a broader range of specified foreign financial assets, including certain foreign investments and ownership interests.
The reporting thresholds are significantly higher than FBAR and vary depending on:
Although both forms involve foreign assets, they serve different purposes.
FBAR focuses primarily on identifying foreign financial accounts.
Form 8938 helps the IRS verify foreign assets that may generate taxable income and improve compliance with US tax laws.
As a result, many taxpayers must report the same account on both forms.
|
Feature |
FBAR |
Form 8938 |
|
Governing Law |
Bank Secrecy Act |
FATCA |
|
Filed With |
FinCEN |
IRS |
|
Filing Method |
Electronic |
Attached to tax return |
|
Purpose |
Report foreign accounts |
Report foreign financial assets |
|
Threshold |
Aggregate foreign account balance exceeds $10,000 |
Higher thresholds depending on taxpayer |
|
Includes Bank Accounts |
Yes |
Yes |
|
Includes Investment Accounts |
Yes |
Yes |
|
Includes Certain Foreign Investments |
Limited |
Yes |
|
Filed Separately |
Yes |
No |
|
Due Date |
April (automatic extension available) |
Tax return due date |
|
Penalties |
Separate |
Separate |
You generally must file FBAR if:
Even if one account had only $500 and another had $9,800, crossing the combined threshold could trigger an FBAR filing requirement.
The thresholds for Form 8938 depend on where you live and your filing status.
|
Filing Status |
End-of-Year Value |
Maximum Value During Year |
|
Single |
$50,000 |
$75,000 |
|
Married Filing Jointly |
$100,000 |
$150,000 |
|
Filing Status |
End-of-Year Value |
Maximum Value During Year |
|
Single |
$200,000 |
$300,000 |
|
Married Filing Jointly |
$400,000 |
$600,000 |
Many US taxpayers living in India or maintaining investments in India are surprised to learn that multiple Indian financial assets may be reportable.
|
Asset |
FBAR |
Form 8938 |
|
NRE Savings Account |
Usually Yes |
May be Yes |
|
NRO Account |
Usually Yes |
May be Yes |
|
Savings Account |
Yes |
May be Yes |
|
Current Account |
Yes |
May be Yes |
|
Fixed Deposits |
Yes |
May be Yes |
|
Recurring Deposits |
Yes |
May be Yes |
|
Demat Account |
Generally Yes |
Usually Yes |
|
Indian Brokerage Account |
Yes |
Usually Yes |
|
Shares of Indian Companies |
No (unless held through reportable account) |
Often Yes |
|
Foreign Mutual Funds |
Depends |
Often Yes |
|
Cash Value Life Insurance |
May Apply |
Often Yes |
|
Foreign Pension Interests |
Facts dependent |
May Apply |
Note: Whether a particular asset is reportable depends on the applicable rules and facts of your situation.
Raj is employed in California.
He maintains:
The combined highest balance during the year reached USD 18,000.
Result:
Raj is generally required to file an FBAR.
Whether Form 8938 is required depends on whether his specified foreign financial assets exceed the applicable threshold.
Priya owns:
Her foreign financial assets total USD 260,000.
She may need to file both FBAR and Form 8938.
An Indian citizen holding a US Green Card relocates to India as part of their Returning to India journey but continues to be a US tax resident.
Although residing in India, US reporting obligations may continue until US tax residency changes under applicable rules.
Foreign accounts maintained in India may still require reporting.
Many taxpayers do.
Use this simple checklist:
File FBAR if:
File Form 8938 if:
Sometimes the answer is:
Assuming FBAR and Form 8938 Are the Same
This is the most common mistake.
Each form has different filing requirements.
Many taxpayers mistakenly believe NRE accounts are exempt from US reporting.
US reporting rules are separate from Indian tax treatment.
Even inactive accounts may require reporting if they meet the applicable criteria.
Joint ownership does not automatically eliminate reporting obligations.
Foreign brokerage accounts, securities accounts, and certain investment accounts may also need reporting.
Account balances should generally be converted using the appropriate prescribed exchange rate for reporting purposes.
Failure to comply with foreign asset reporting requirements can lead to significant consequences.
Potential issues include:
The applicable penalty depends on the facts, the type of violation, and whether the failure is considered willful or non-willful.
If you discover that you missed prior filings, it is generally advisable to seek professional advice before submitting late forms.
Navigating US international reporting requirements can be challenging, especially for taxpayers with financial ties to India.
Our cross-border tax professionals assist clients with:
Whether you are a US citizen living in India, a Green Card holder, an H-1B professional, or a returning Indian, we help ensure your reporting obligations are addressed accurately and efficiently.
If you have bank accounts, investments, or other financial assets outside the United States, determining your reporting obligations is an important part of your annual US tax compliance.
Our team of Chartered Accountants and US tax professionals provides comprehensive assistance with US tax filing, FBAR reporting, FATCA compliance, and broader cross-border tax planning for individuals with India-US financial connections.
Contact Dinesh Aarjav & Associates to discuss your reporting requirements and ensure your US tax filings are completed with confidence.


Stay in the loop, subscribe to our newsletter and unlock a world of exclusive updates, insights, and offers delivered straight to your inbox.
.webp)


