WhatsApp
 Call Us
 Email Us
 Whatsapp Community

Would you like to schedule a call back
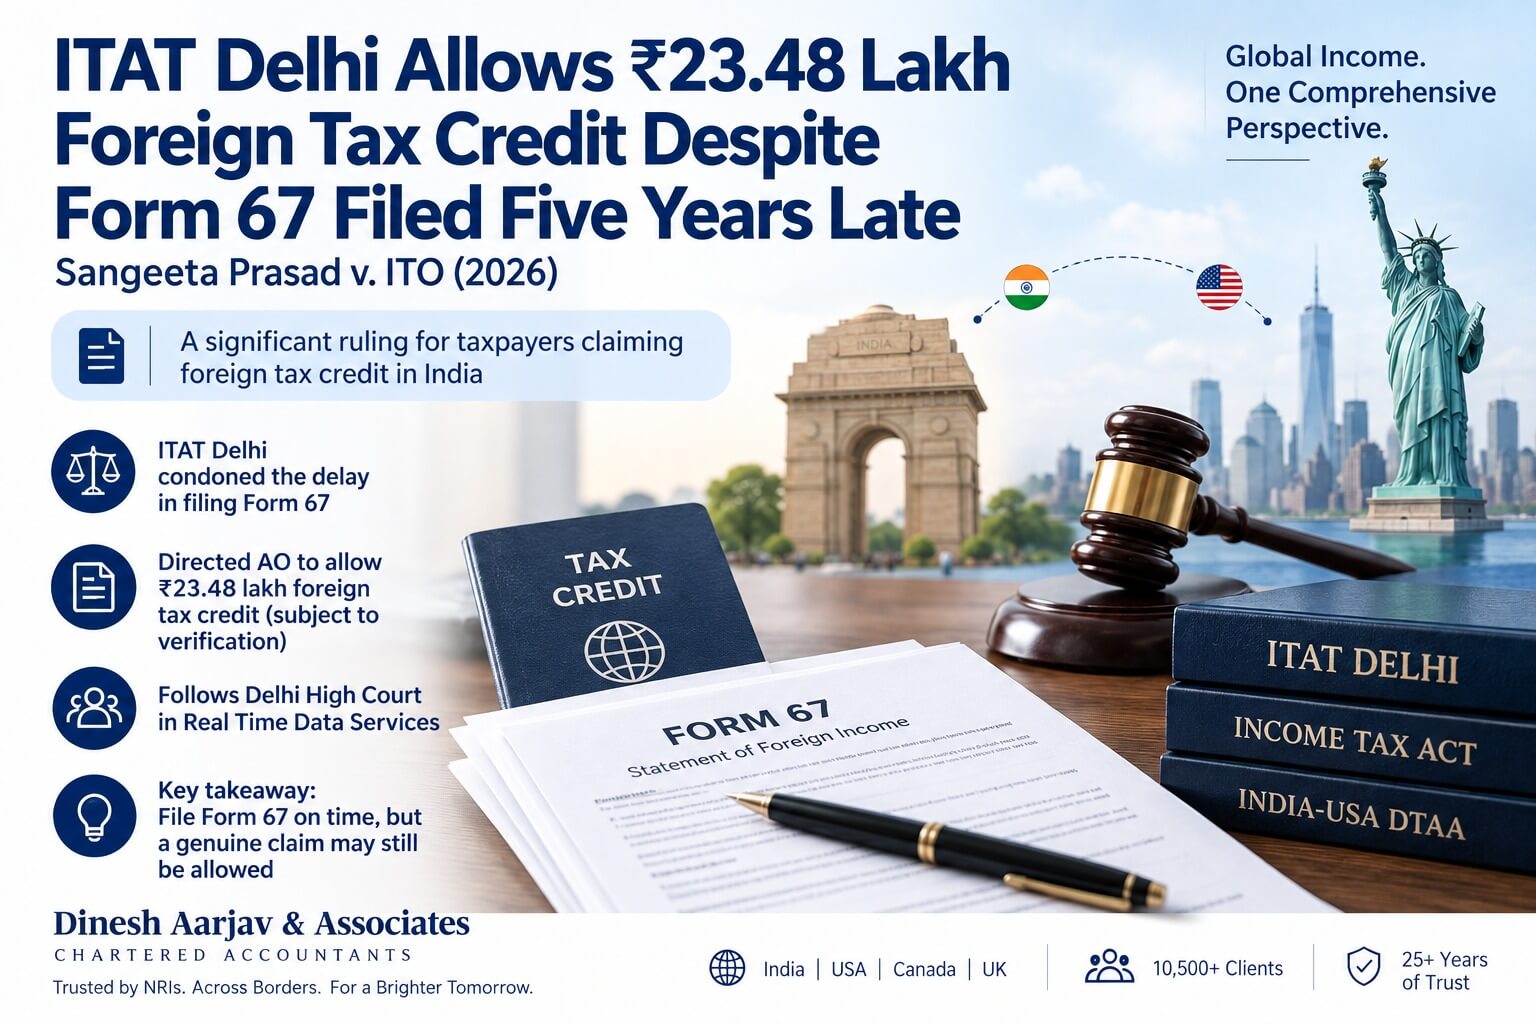


In Sangeeta Prasad v. ITO (ITA No. 1393/Del/2026, AY 2018-19, order dated 14 September 2026), ITAT Delhi condoned a delay of nearly five years in filing Form 67 and directed the Assessing Officer to allow foreign tax credit of ₹23,48,278 for tax paid in the USA, subject to verification. The Tribunal followed the Delhi High Court in Real Time Data Services (P.) Ltd. v. PCIT and held that a late Form 67 is a technical lapse that cannot destroy the substantive right to credit under Section 90 and Article 25 of the India-USA DTAA. The ₹30,63,510 demand raised only because the form was missing now has to be recomputed.
Here is why this particular order carries more weight than most Form 67 decisions, and how you can use it if CPC has denied your own credit.
A US citizen who was tax-resident in India paid tax in the USA, reported that income in her Indian return, and claimed credit for the US tax. She never filed Form 67. CPC Bengaluru stripped out the credit and raised a demand of over ₹30 lakh. Six years and two rejected rectifications later, ITAT Delhi gave her the credit back.
The facts were about as unhelpful for a taxpayer as they get. The form wasn't a week or a month late. It was filed in February 2023 against a return filed in August 2018. Even the relaxed deadline the CBDT introduced in 2022 had been missed by years. The Tribunal still sided with her.
| Particular | Details |
|---|---|
| Case name | Sangeeta Prasad (USA) v. Income Tax Officer, Ward-4(1), Gurgaon |
| Appeal number | ITA No. 1393/Del/2026 |
| Bench | ITAT Delhi Bench 'G', Shri Ramit Kochar (AM) and Shri Vimal Kumar (JM) |
| Counsel for taxpayer | Shri Snehil Jha and Shri Shishir Jha |
| Assessment year | AY 2018-19 |
| Hearing / order date | 23 June 2026 / 14 September 2026 |
| Issue | FTC denied under Sections 90/90A for late Form 67 under Rule 128(9) |
| FTC in dispute | ₹23,48,278 (tax paid in the USA) |
| Demand raised | ₹30,63,510 |
| Precedent followed | Real Time Data Services (P.) Ltd. v. PCIT [2026] 183 taxmann.com 701 (Delhi HC) |
| Outcome | Appeal allowed; delay condoned; AO to allow FTC after verification |
She was a US citizen living in Tucson, Arizona, who was tax-resident in India for the year in question. That single fact is what made the claim possible, and most summaries skip it.
Foreign tax credit under Rule 128 is a relief for residents. A resident is taxed in India on global income, so her US income entered the Indian return and the US tax already paid on it was set off against the Indian liability. The India-USA DTAA lets India collect only the differential tax.
A pure non-resident normally never reaches this point, because foreign income of an NRI isn't taxable in India at all. The people who actually fall into this trap are:
The sequence matters, because it shows the Department had several chances to fix this and took none of them.
| Date | Event |
|---|---|
| 28 Aug 2018 | ITR filed under Section 139(1) for AY 2018-19 claiming FTC of ₹23,48,278. Form 67 not filed. |
| 9 May 2019 | CPC Bengaluru transfers the return to the jurisdictional AO, unable to verify foreign taxes. |
| 21 Mar 2020 | CPC issues Section 143(1) intimation denying FTC and raising a demand of ₹30,63,510. |
| 28 Mar 2020 | First rectification application under Section 154 filed online. |
| 24 Jun 2020 | CPC rejects the rectification. FTC denied again. |
| 8 Feb 2023 | Form 67 finally filed, claiming the same ₹23,48,278. |
| 20 Feb 2025 | Second Section 154 application filed with the jurisdictional AO. |
| 13 Mar 2025 | AO rejects it: Form 67 not filed within the prescribed time. |
| 16 Jan 2026 | CIT(A) (NFAC) dismisses the appeal under Rule 128(9). |
| 14 Sep 2026 | ITAT Delhi allows the appeal and directs the AO to grant FTC after verification. |
Look closely at the gap between May 2019 and March 2020. CPC itself said it couldn't verify the foreign tax and sent the file to the jurisdictional AO. The AO started nothing. No verification, no query, no notice. CPC then processed the return anyway and removed the credit. The Tribunal picked up on that, and so should anyone drafting a similar appeal.
The Revenue's case was short and, on a literal reading, not unreasonable.
Her counsel built the appeal on four pillars.
She also said plainly that she was unaware of the Form 67 obligation and asked for the delay to be condoned.
ITAT Delhi condoned the five-year delay and directed the AO to allow the credit after verifying the documents, with a proper hearing for the taxpayer. If the AO still refuses, he has to pass a speaking order giving reasons, which she can then challenge.
The Bench first set out the undisputed facts. The return was filed on time. The credit was claimed in it. Form 67 came only in February 2023, long after processing. CPC had transferred the case for verification but the AO never began any. No Section 139(9) notice and no proviso notice under Section 143(1) were issued before the credit was disallowed.
Then it turned to the jurisdictional High Court. In Real Time Data Services (P.) Ltd. v. PCIT, the Delhi High Court dealt with a company that missed the Form 67 deadline and lost FTC of over ₹1 crore. The Court called the failure a "technical or venial breach" and held the substantive right to credit survives it. Keeping the money, the Court said, would mean withholding a substantial sum without authority of law, which is unjust enrichment. It directed the AO to allow the credit after verification once the form was on record, or pass a speaking order.
The Tribunal respectfully followed that judgment and allowed the appeal.
A mandatory provision is one where non-compliance kills the right. A directory provision tells you how and when to do something, but missing it doesn't destroy the entitlement underneath.
The credit itself flows from Section 90 and Article 25 of the India-USA DTAA. Rule 128 only prescribes the manner of claiming it. Nothing in Rule 128(9) says the credit is forfeited if the statement arrives late. Courts and tribunals have read that silence in the taxpayer's favour for years, and with the Delhi High Court now saying it squarely, AOs and CIT(A)s in Delhi have a binding precedent in front of them.
This is worth being precise about, because write-ups on rulings like this often overstate them.
The Tribunal gave no separate finding on whether the 143(1) intimation was void for want of prior notice, or whether Section 154 was the correct remedy. It didn't need to. Having condoned the delay on the strength of the High Court judgment, it granted relief on merits.
So if you rely on this order, lean on the Form 67 reasoning. The jurisdictional grounds stay arguable in your own case, but this order is not authority for them.
Form 67 must be filed electronically, and the deadline has moved twice since 2017. Here is where things stand.
| Period | Deadline under Rule 128(9) | Practical position |
|---|---|---|
| 1 April 2017 to the 2022 amendment | On or before the Section 139(1) due date | CPC denied FTC wherever the form was late, even by a day |
| After CBDT Notification No. 100/2022 (18 Aug 2022) | End of the assessment year, if the return is filed under Section 139(1) or 139(4) | More breathing room, but later filings still get auto-rejected at processing |
| Judicial view (Delhi HC, Gujarat HC, several ITAT benches) | Treated as directory | A late form shouldn't defeat a genuine claim, but you usually have to litigate |
| Income-tax Act, 2025 (from 1 April 2026) | Form 67 is replaced by Form 44 under the new law | The principle carries over; cite the new provisions correctly in fresh filings |
For AY 2018-19, the year in this case, the deadline was the Section 139(1) due date falling in 2018. Her form arrived in 2023. That is exactly what makes this ITAT Delhi foreign tax credit ruling significant: the Bench condoned a delay that no version of the rule would have forgiven on its own terms.
If you're moving back to India or already living here on a US passport, this order is your safety net when Form 67 slips.
The year of return is when the problem usually bites. You become resident, your US salary, 401(k) withdrawals or brokerage income land in the Indian return, and the software invites you to claim credit. What it does not do is warn you loudly that a separate Form 67, with proof of foreign tax paid, has to go in before the deadline.
US citizens and green card holders face it every single year, because the US taxes on citizenship. Resident Indians holding US RSUs or ESPP shares see US withholding on dividends and sometimes on sale proceeds. In each case, a missing form creates a demand for tax you've already paid once.
There's a limit, though. The relief was granted "subject to verification". The AO will still want proof that the US tax was actually paid on income that was also taxed in India:
A late Form 67 can be forgiven. A credit you can't document cannot.
Start with the cheapest remedy and escalate only if it fails.
| Remedy | When it fits | Watch out for |
|---|---|---|
| File Form 67 now | Always the first step, even after the deadline | The portal may accept it, but that alone doesn't reverse the demand |
| Rectification under Section 154 | Where the form is on record and denial is purely for lateness | Revenue often argues this isn't a mistake apparent from record |
| Appeal to CIT(A) | Against the 143(1) intimation or a rejected 154 order | Deadlines apply; ask for condonation with reasons if you're late |
| Revision under Section 264 | Where you want the Commissioner to use his discretion | Delhi HC in Real Time Data said the Commissioner should have condoned the default |
| Appeal to ITAT or writ to High Court | When lower authorities refuse relief | Cite Real Time Data Services, Deepak Pragjibhai Gondaliya and this order |
Most FTC disputes we handle trace back to one of five avoidable errors.
This order doesn't create new law. What it does is apply the Delhi High Court's Real Time Data Services judgment to about the hardest facts imaginable: a five-year delay, two rejected rectifications, and a CIT(A) order against the taxpayer. If the Tribunal condoned that, someone who missed the deadline by a few months stands on very firm ground.
Even so, we'd never advise planning around litigation. It took this taxpayer from 2020 to 2026 to get a direction the AO must still act on. File Form 67 before you file the return, keep your US transcripts ready, and if you're returning to India, map your residential status before the first Indian return. The cheapest FTC dispute is the one you never have.
At Dinesh Aarjav & Associates, we handle FTC claims, Form 67 filings and litigation over denied credits for NRIs, returning NRIs, OCI holders and US citizens resident in India. If CPC has disallowed your credit, or you're moving back and want your first Indian return done right, reach out through our NRI & OCI Services page or our Returning to India desk.
CA Dinesh K. Jain is the Founder and Mentor of Dinesh Aarjav & Associates, with over 35 years of experience in NRI taxation, cross-border advisory, project financing, and tax litigation. He has guided numerous NRIs and global families through complex tax and regulatory matters involving investments, repatriation, and international financial planning.


Stay in the loop, subscribe to our newsletter and unlock a world of exclusive updates, insights, and offers delivered straight to your inbox.
.webp)