WhatsApp
 Call Us
 Email Us
 Whatsapp Community

Would you like to schedule a call back
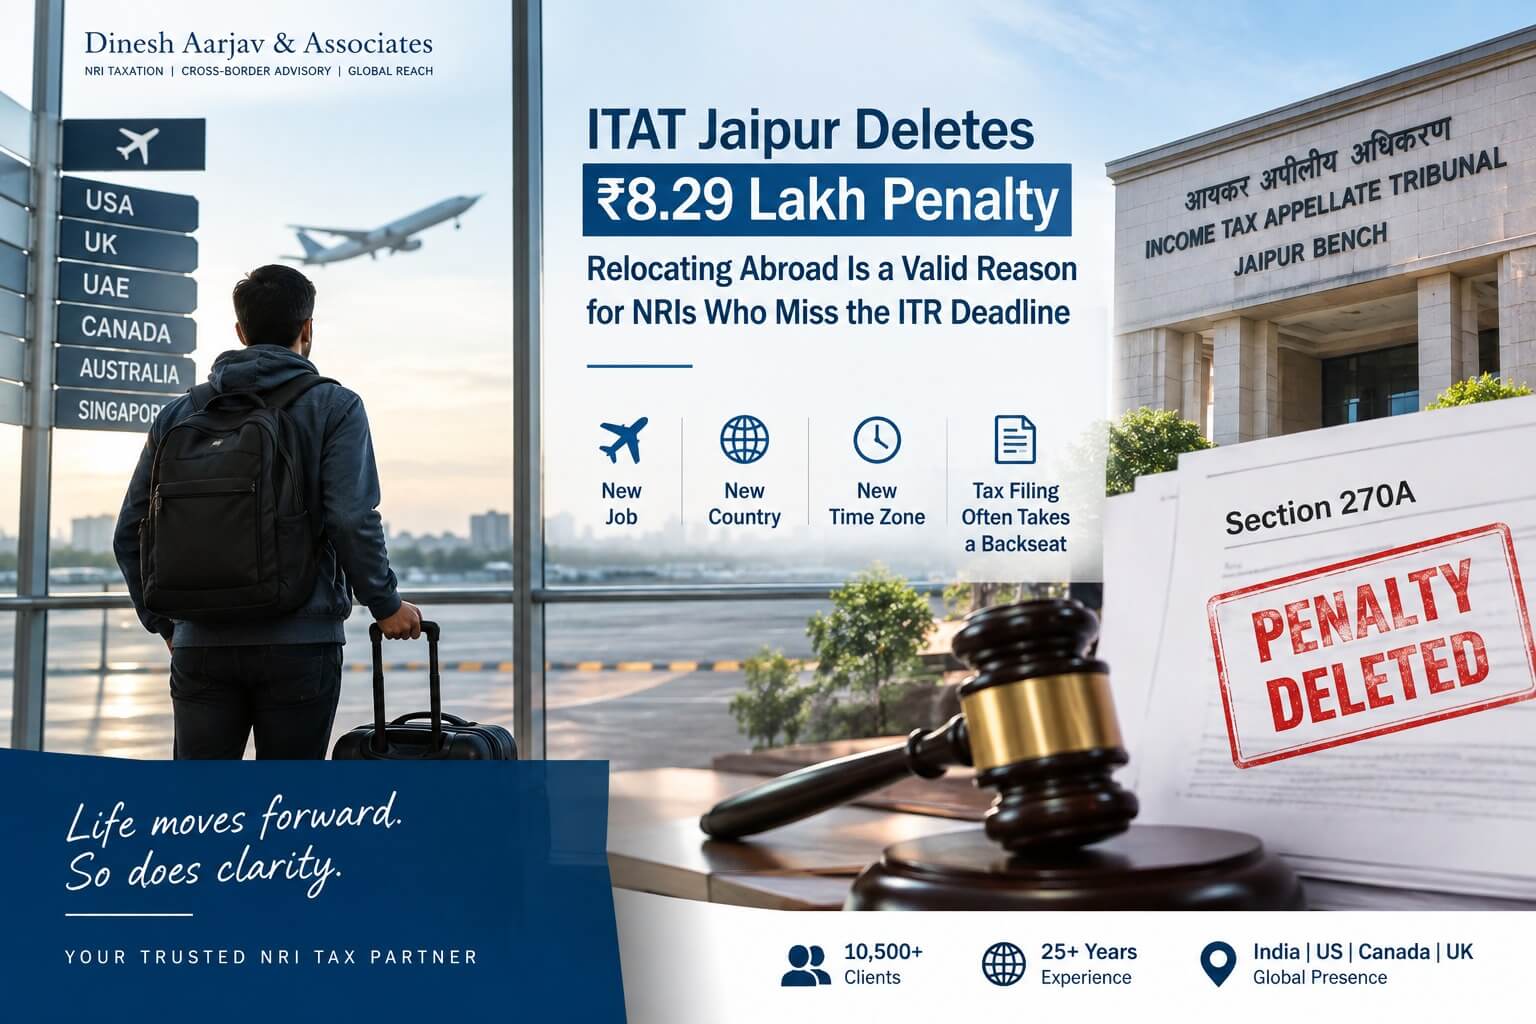


When someone moves abroad for a new job, filing an Indian income tax return is rarely at the top of the to-do list. New city, new time zone, a hundred things to settle. By the time the ITR deadline comes to mind, it has often already passed.
What this ruling confirms is that missing a deadline because of a genuine relocation, followed by voluntary tax payment before any notice arrives, does not automatically mean a penalty will stick. The Income Tax Appellate Tribunal, ITAT Jaipur, recently deleted a Section 270A penalty of ₹8.29 lakh on exactly this basis, in the case of Abhishubham Bahadur Saxena vs ITO (ITA No. 668/JPR/2026).
This is directly relevant for NRIs in the USA, UK, UAE, Canada, Australia, Singapore, and elsewhere who moved abroad mid-year and missed a filing deadline, or who have already received an income tax notice in India.
The taxpayer moved to the United States in August 2018 for a job with a multinational company. In the middle of settling into a new country and a demanding role, he missed the 31 August 2018 deadline to file his return for AY 2018-19. During that year, he had earned salary income of around ₹26.05 lakh.
By the time he caught the oversight, in August 2019, the window to file a belated return under Section 139(4) had already closed. Rather than do nothing, he voluntarily deposited self-assessment tax of roughly ₹1.62 lakh, along with interest and the late fee under Section 234F. He did this well before the Income Tax Department issued any notice.
The Department reopened his case under a Section 148 reassessment notice in March 2022. He filed a return declaring total income of ₹20.49 lakh, which the Department accepted without any changes. Despite this, the Assessing Officer initiated penalty proceedings under Section 270A(9), treating the income as both underreported and misreported, and levied a penalty of ₹8.29 lakh. The Commissioner (Appeals) upheld it. The case went to ITAT Jaipur.
This is the core question, and the answer depends on a few specific provisions.
Section 270A(2)(b) treats income as "underreported" when a return is filed for the first time only in response to a Section 148 reassessment notice, and the assessed income exceeds the basic exemption limit. Section 270A(9)(a) goes further: it treats that underreporting as "misreporting" if there is misrepresentation or suppression of facts, which attracts a much steeper penalty.
On a plain reading, the Department's position was not unreasonable. No original return was filed. Income was disclosed only after a notice. Assessed income exceeded the threshold. All of that, on the face of it, fits the definitions.
But the law includes an important exception that changes the picture.
The Tribunal looked at Section 270A(6)(a), which says income does not qualify as underreported at all if the taxpayer offers a bona fide explanation and discloses all material facts to back it up. And if the income was never underreported in the first place, the misreporting charge cannot survive either.
The ITAT Jaipur bench found the taxpayer's explanation genuinely bona fide, based on the following:
On this basis, the Tribunal held that the explanation was bona fide and properly substantiated, and that the Assessing Officer and CIT(A) were wrong to disallow it. Since the income never qualified as underreported under Section 270A(6), the entire ₹8.29 lakh Section 270A penalty was directed to be deleted.
The Tribunal also condoned a 49-day delay in filing the appeal itself. The delay happened because the taxpayer's PAN was showing an outdated Kanpur jurisdiction on the portal instead of Jaipur. The ITAT accepted that this was a procedural issue, not any laxity on the taxpayer's part.
This case reflects a fact pattern that comes up regularly for first-time NRIs and recently relocated professionals. A few lessons stand out clearly.
The single most important fact here was that the taxpayer paid his taxes before the Department issued any notice. Once a notice arrives first and compliance follows only afterward, the bona fide argument becomes much harder to sustain.
ITAT Jaipur specifically noted that the taxpayer had always filed on time in earlier years. That track record supports the argument that the lapse was a one-time, genuine oversight, not a pattern of avoidance.
Section 270A(6) is not automatic. The taxpayer has to actively demonstrate bona fides with clear evidence: a timeline of events, proof of voluntary payment, and records showing the reason for the delay. Without that paper trail, the protection is hard to claim.
As data-matching between banks, employers, and the Income Tax Department improves, more NRIs are receiving Section 148 reassessment notices years after relocating. Often these relate to the very year they were transitioning between countries.
Whether you are yet to file or have already received a notice, the steps to take are similar.
Getting these details wrong can make an already stressful situation considerably worse.
Assuming the ITR deadline no longer applies after you leave India. Indian-source income, and worldwide income earned while you were still a resident during that financial year, must be reported regardless of where you are living when the deadline falls.
Waiting for a notice before doing anything. As this ruling makes clear, voluntary compliance before a notice is the factor that makes a bona fide explanation credible. Waiting for the Department to act first weakens that argument considerably.
Not keeping evidence of the relocation itself. Boarding passes, offer letters, employment start dates, and payment challans all matter when a bona fide explanation has to be substantiated years down the line.
Missing the belated return window under Section 139(4). The window to file a belated return is limited and closes at the end of the relevant assessment year. Once it closes, that option is gone.
Treating a Section 148 reassessment notice as routine. These notices carry real consequences, including Section 270A penalty exposure, and deserve a carefully drafted response.
Our team regularly helps NRIs, OCIs, and recently relocated professionals with NRI ITR filing and tax notice matters in India.
| Service Area | What We Cover |
|---|---|
| NRI ITR Filing | Income tax return filing for NRIs, including belated and reassessment returns; residential status advisory for the year of relocation |
| Income Tax Notice Reply | Responses to Section 148 reassessment notices; Section 270A and 270AA penalty representations; defective return and scrutiny matters |
| Cross-Border Tax Advisory | DTAA advisory for NRIs in the USA, UK, UAE, Canada, Australia, and Singapore; compliance planning for the year of moving abroad or returning to India |
With 25+ years of experience focused on NRI and cross-border taxation, we help clients build the documented, bona fide compliance record that tribunals like ITAT Jaipur look for in cases like this one.
CA Dinesh K. Jain is the Founder and Mentor of Dinesh Aarjav & Associates, with over 35 years of experience in NRI taxation, cross-border advisory, project financing, and tax litigation. He has guided numerous NRIs and global families through complex tax and regulatory matters involving investments, repatriation, and international financial planning.


Stay in the loop, subscribe to our newsletter and unlock a world of exclusive updates, insights, and offers delivered straight to your inbox.
.webp)