WhatsApp
 Call Us
 Email Us
 Whatsapp Community

Would you like to schedule a call back
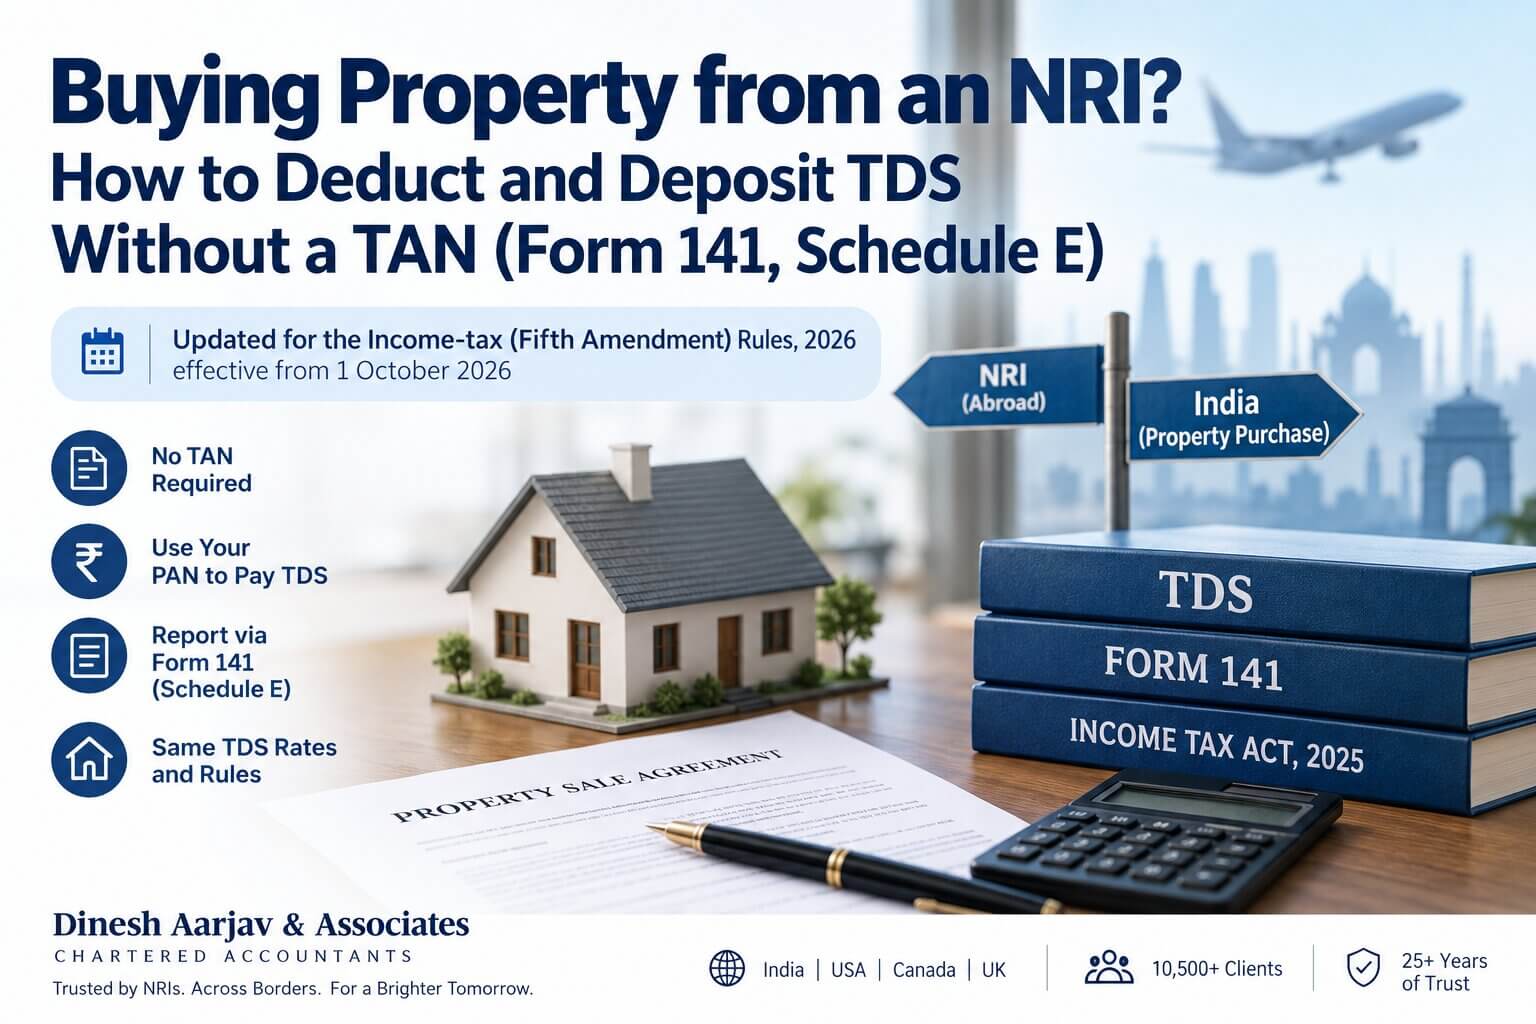


From 1 October 2026, a resident individual or HUF buying immovable property from an NRI does not need a TAN to deduct and deposit TDS. You can now pay and report the tax using your own PAN through Form 141, the challan-cum-statement, by filling the newly inserted Schedule E. The TDS rate and the amount on which tax is deducted have not changed. Only the paperwork has.
This is based on the Income-tax (Fifth Amendment) Rules, 2026, notified by CBDT vide G.S.R. 830(E) dated 22 September 2026, effective 1 October 2026, under Section 393(2) of the Income-tax Act, 2025.
If you are buying a flat, house, plot or commercial unit from an NRI, this is probably the most useful compliance change of the year for you. Until now, this was the one property deal where an ordinary household buyer had to register as a deductor, get a TAN, file a quarterly TDS return and issue a certificate to the seller, all for a single transaction. Most buyers had never heard of a TAN until their lawyer or banker said the word. Plenty found out only when a late-filing notice landed.
This guide is written for the buyer. If you are the NRI selling, our guides on TDS on sale of property by NRI and the lower or nil TDS certificate (Form 128) cover your side.
The CBDT amended three rules and two forms. Read together, they move NRI-seller property deals onto the same simplified track that resident-seller purchases have always used.
|
Provision |
What the amendment does |
What it means for you |
|
Rule 215(1) |
Adds TDS under Section 393(2) [Table Sl. No. 17] on transfer of immovable property, where the deductor is a resident individual or HUF, to the challan-cum-statement list |
No TAN needed. You use your PAN |
|
Rule 218(3) |
Brings such consideration within the payment rules for challan-cum-statement deductions |
Deposit timeline aligns with resident-seller deals |
|
Rule 219(5) |
Requires the TDS certificate to be issued through the same simplified route |
Seller gets a transaction-specific certificate, no waiting for a quarterly return |
|
Form 141 |
Heading expanded to cover Section 393(2); new option for transfer of immovable property by a non-resident; Schedule E inserted |
One form per transaction covers payment and reporting |
|
Form 132 |
Matching option added for property transfer by a non-resident to a resident individual or HUF |
Supporting form aligned with the new route |
Here is the change at a glance.
|
Step |
Before 1 October 2026 |
From 1 October 2026 |
|
Registration |
Buyer had to apply for a TAN |
No TAN. Buyer's PAN is enough |
|
Payment of TDS |
Challan under TAN |
Form 141 challan-cum-statement with Schedule E |
|
Reporting |
Quarterly TDS return for non-resident payments |
Same Form 141, per transaction |
|
Certificate to seller |
After the quarterly return was processed |
Through the simplified route linked to Form 141 |
|
Typical buyer pain point |
Late fees and notices for a return the buyer never knew about |
Getting the seller's details right in Schedule E |
The relief is procedural. It is not a tax cut, and the headlines can give the wrong impression.
Buying from an NRI and buying from a resident are two different compliance worlds, even after the 2026 simplification. This table is the one most buyers get wrong.
|
Parameter |
Seller is resident |
Seller is an NRI |
|
Governing provision |
Section 393(1), the old Section 194-IA |
Section 393(2), the old Section 195 |
|
Rate |
1% of consideration |
12.5% plus surcharge and cess (LTCG) or slab rate (STCG) |
|
Threshold |
₹50 lakh |
None. Any value |
|
TAN |
Not required |
Not required from 1 Oct 2026 for resident individual or HUF buyers. Still required for companies, firms and LLPs |
|
Form used |
Challan-cum-statement |
Form 141 with Schedule E |
|
Lower deduction certificate |
Rarely used |
Common and worth asking about |
Note on holding period: property is long-term when held for more than 24 months. Anything shorter is short-term and is deducted at slab rates, which usually means 30% plus surcharge and cess.
The test is the buyer's residential status, not citizenship or where the money comes from.
|
Buyer or property type |
Can use Form 141 without TAN? |
|
Resident individual buying from an NRI |
Yes |
|
HUF buying from an NRI |
Yes |
|
Company, firm or LLP buying from an NRI |
No. The TAN route with periodic returns continues |
|
Land (other than agricultural land) |
Yes |
|
Building or part of a building |
Yes |
|
Land and building together |
Yes |
|
Not covered by Schedule E |
One point that catches people out: an OCI cardholder who is resident in India for the tax year can use this route when buying from an NRI. An NRI buying from another NRI cannot, because the deductor must be resident.
Schedule E is far more detailed than the form resident-seller buyers are used to. Here is what each block covers and where buyers usually get stuck.
|
Schedule E field |
What to fill in |
Practical note |
|
Property address and type |
Address; land (non-agricultural), building, or both |
Match the sale agreement exactly |
|
Details of all buyers |
PAN, name and share of consideration for each buyer |
Shares must total 100% |
|
Details of all sellers |
PAN (if available), name, status code, phone, email, foreign address, TRC number, foreign TIN, share of consideration |
Foreign contact details are mandatory even if the seller has a PAN |
|
Date of agreement and registration |
dd/mm/yyyy |
Registration date only if available |
|
Stamp duty value and sale consideration |
Total SDV and total consideration |
Keep the stamp valuation document handy |
|
Lumpsum or instalments |
First, subsequent or last instalment, with the previous acknowledgement number |
Save every acknowledgement number |
|
Seller's tax regime |
Whether the seller is opting out of the default regime under Section 202(1) |
Ask the seller in writing |
|
Type of capital gain |
LTCG under Section 197(1) or STCG (other than Section 196) |
Depends on the holding period |
|
Certificates |
Section 395(1) certificate number (seller's) or Section 395(2) certificate number (buyer's) |
Deduct only at the certified rate |
|
TDS details |
Amount liable, rate, TDS amount, date of deduction |
TDS must include surcharge and cess |
|
Form 145 acknowledgement |
Acknowledgement number of the related Form 145, if applicable |
Relevant where remittance reporting applies |
Normally, no PAN means a higher TDS rate. Schedule E lets you furnish the seller's tax residency certificate number and foreign tax identification number instead, in line with Rule 217, so the higher rate does not apply.
This only works if the seller actually holds a valid TRC. Without one, you are back to the higher rate. Our advice is still to get the seller a PAN well before the deal, because they will need it for Form 128, their Indian return and any refund anyway.
You deduct TDS on each payment, deposit it with Form 141 using your PAN, and hand the seller a certificate. Here is the full sequence.
Form 141 follows the challan-cum-statement timeline that resident-seller buyers already use, so the deposit is tied to the month in which you deducted. Miss it and interest runs at 1% a month for late deduction and 1.5% a month for late deposit, plus late-filing fees. Deposit early rather than on the last day; bank cut-offs cause more defaults than forgetfulness does.
Numbers make this clearer than rules do.
Mr. and Mrs. Sharma, both resident, jointly buy a flat in Gurugram from an NRI based in Dubai for ₹1.2 crore. The seller has held the flat for six years, so the gain is long-term. No lower deduction certificate is in place.
|
Particulars |
Amount |
|
Sale consideration |
₹1,20,00,000 |
|
Base rate (LTCG) |
12.5% |
|
Surcharge (₹1 crore to ₹2 crore band) |
15% |
|
Health and education cess |
4% |
|
Effective TDS rate |
14.95% |
|
Total TDS |
₹17,94,000 |
|
Mr. Sharma's share (50%), separate Form 141 |
₹8,97,000 |
|
Mrs. Sharma's share (50%), separate Form 141 |
₹8,97,000 |
Two things stand out. Each spouse is a separate deductor and files a separate Form 141, which the notes to Schedule E state expressly. And if the seller's actual gain was only ₹25 lakh, nearly ₹18 lakh is still withheld unless a certificate is in place.
That gap is exactly why sellers who plan ahead apply for a lower deduction certificate before the agreement, and why buyers should raise it early.
The only clean way to cut the deduction is a certificate from the Income Tax Department, not a private arrangement with the seller.
Never agree to deduct less because the seller says their gain is small. If the department disagrees later, the shortfall, interest and penalty land on you.
Put these in writing, ideally as an annexure to the agreement to sell, so nothing is chased on the day of payment.
Most defaults come from a handful of avoidable errors.
The form states that the TDS amount must include surcharge and cess. Deducting a flat 12.5% on a ₹1.5 crore deal leaves a shortfall of more than ₹3.6 lakh, and that shortfall is your problem.
Couples assume one form covers the purchase because the flat is one asset. It doesn't. Each deductor files separately for their share.
The 1% rate and the ₹50 lakh threshold do not apply. Buyers still deduct 1% because a property portal showed that figure.
If the seller turns out to be non-resident and you deducted as though they were resident, the shortfall is yours to fund.
Every instalment filing needs the previous acknowledgement number. Keep a simple log from the first payment.
On our reading, the new route applies from the date the amended rules take effect. Deductions made earlier follow the older TAN-based process. If your deal straddles the date, take advice on the earlier instalments.
Sellers gain too, mostly in speed. Under the old system, TDS credit appeared only after the buyer filed a quarterly return, and many buyers filed late or not at all.
With one Form 141 per transaction, the credit and the certificate should reach the seller faster. That makes it easier to file the Indian return, claim a refund where the actual gain is lower than the amount withheld, and move on to repatriation.
Repatriation itself still needs the usual remittance paperwork through the authorised dealer bank, including the chartered accountant certification, before funds leave the NRO account. For the full seller-side process, see our Sale of Property in India services and our guide on capital gains tax for NRIs.
We handle both sides of these deals every week: computing the correct TDS for resident buyers, filing Form 141 with Schedule E, and helping NRI sellers get lower deduction certificates and repatriate their proceeds.
If you are about to sign with an NRI seller, one short call before the first payment can prevent an expensive correction later.
Book a consultation: WhatsApp +91-98999 69645 or explore our NRI and OCI Services
Aarjav Jain is the Executive Director at Dinesh Aarjav & Associates, specializing in India–US cross-border transactions, NRI taxation, international tax advisory, and global investment structuring. With over 10 years of experience in project financing and cross-border advisory, he assists NRIs and businesses with regulatory compliance, repatriation planning, and international transaction structuring.
Stay in the loop, subscribe to our newsletter and unlock a world of exclusive updates, insights, and offers delivered straight to your inbox.
.webp)