WhatsApp
 Call Us
 Email Us
 Whatsapp Community

Would you like to schedule a call back
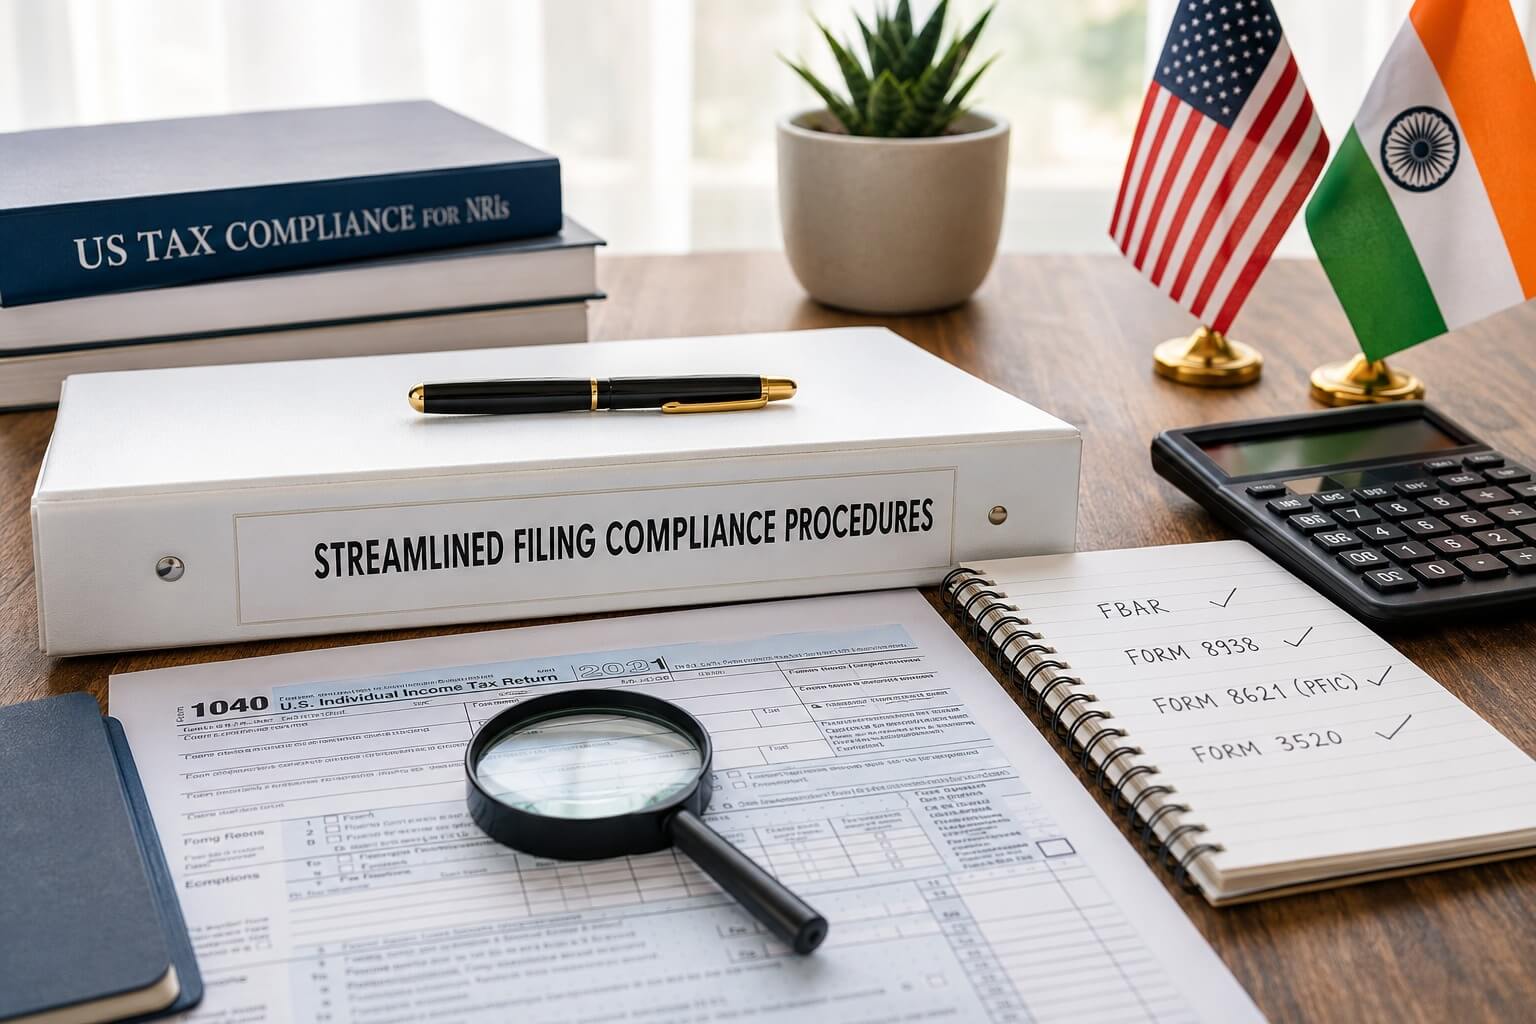


Many Non-Resident Indians (NRIs), H-1B visa holders, Green Card holders, and returning Indians discover years after moving to the United States that they were required to report their foreign bank accounts, Indian investments, or overseas income to the IRS.
Often, this realization comes only after changing tax advisors, applying for a Green Card, planning to return to India, or learning about international tax reporting obligations such as the FBAR, Form 8938, or PFIC reporting.
The good news is that making an honest mistake does not always lead to severe penalties. The IRS provides a structured path for eligible taxpayers to voluntarily correct past filing errors through the Streamlined Filing Compliance Procedures.
For many taxpayers whose mistakes were non-willful, these procedures provide an opportunity to become compliant with US tax laws while significantly reducing potential penalties compared to waiting for the IRS to discover the omission.
In this guide, we explain:
This means that once you become a US tax resident, your reporting obligations may extend far beyond your US salary or investments. Depending on your circumstances, you may also need to disclose:
Unfortunately, many taxpayers remain unaware of these requirements because:
These misunderstandings are extremely common among first-generation immigrants and globally mobile professionals.
The Streamlined Filing Compliance Procedures are an IRS compliance program designed for taxpayers who unintentionally failed to meet certain US tax filing and international reporting obligations.
Rather than waiting for the IRS to initiate an examination, eligible taxpayers can voluntarily correct past mistakes by filing amended or delinquent returns, required international information forms, and a certification explaining why the failures occurred.
The procedures are intended for taxpayers whose failures were non-willful, meaning they resulted from negligence, inadvertence, misunderstanding of the law, or a genuine mistake rather than an intentional attempt to avoid taxes or conceal assets.
It is important to understand that the Streamlined Procedures are not a tax amnesty program. Taxpayers must still:
Each submission is made under penalties of perjury, making accuracy and proper documentation critical.
International reporting requirements can carry penalties that are disproportionately high compared to the amount of tax involved.
For example, taxpayers may discover they failed to file:
In many cases, the underlying income may already have been taxed in India, resulting in little or no additional US tax after claiming foreign tax credits. However, the information reporting obligations remain separate from the tax liability itself.
The Streamlined Procedures provide a structured way for eligible taxpayers to address both tax and information reporting deficiencies before they become a larger compliance issue.
This article is particularly relevant if you are:
At Dinesh Aarjav & Associates, many cross-border tax consultations begin with statements such as:
Generally, non-willful conduct includes situations where the taxpayer:
Examples may include:
By contrast, intentionally concealing offshore accounts, deliberately omitting income, or knowingly ignoring filing obligations would generally not be considered non-willful.
Because each case depends on its specific facts, taxpayers should carefully evaluate their circumstances before making any certification.
The IRS offers two primary versions of the Streamlined Filing Compliance Procedures, depending on where the taxpayer resides and whether they satisfy the applicable residency requirements.
|
Feature |
Foreign Offshore Procedures |
Domestic Offshore Procedures |
|
Generally intended for |
Taxpayers meeting the foreign residency requirements |
Eligible taxpayers residing in the US |
|
Residency requirement |
Must satisfy the applicable foreign residency test |
US residents who do not meet the foreign residency test |
|
Non-willful certification required |
Yes |
Yes |
|
Previously unreported income corrected |
Yes |
Yes |
|
International reporting corrected |
Yes |
Yes |
|
Additional tax and interest payable |
Yes |
Yes |
|
Penalty treatment |
Depends on eligibility under the applicable IRS procedures |
Depends on eligibility under the applicable IRS procedures |
Determining which procedure applies requires a careful review of the taxpayer's residency, filing history, and facts. Professional advice is often recommended before making a submission.
Depending on the facts of the case, a Streamlined submission may address:
The exact forms required vary based on the taxpayer's financial assets, entity ownership, investment holdings, and reporting history.
You may wish to review your prior filings if any of the following apply:
Identifying these issues early allows taxpayers to assess their compliance options before the IRS initiates any examination or inquiry.
While the existence of foreign accounts does not automatically imply non-compliance, taxpayers who become aware of filing omissions should evaluate their position proactively rather than waiting for an IRS notice.
Taking timely advice can help determine the most appropriate compliance path based on the taxpayer's individual facts, reporting history, and eligibility under the applicable IRS procedures.
One of the biggest misconceptions among NRIs is that the Streamlined Filing Compliance Procedures are only about filing missed US tax returns.
In reality, many submissions involve correcting international information reporting that should have accompanied those returns. These reporting obligations are separate from the tax return itself and, in some cases, may apply even when no additional US tax is payable.
For NRIs with assets in India, the most commonly overlooked reporting requirements include:
Understanding which forms apply is often the most challenging part of becoming compliant.
For many NRIs, Indian mutual funds are the single largest compliance issue when filing US tax returns.
Most Indian mutual funds are generally classified as Passive Foreign Investment Companies (PFICs) under US tax rules. While the exact classification depends on the facts and structure of the investment, many Indian equity, debt, hybrid, index, and international mutual funds commonly fall within the PFIC regime.
Unlike India, where mutual funds are a routine investment, the US applies a separate tax framework that can significantly increase reporting complexity.
Why PFICs Matter
Owning a PFIC is not prohibited. The challenge lies in the reporting requirements and the way gains and distributions may be taxed under US law.
Depending on the circumstances, PFIC ownership may require:
Many taxpayers discover these obligations only after several years of filing US returns.
Examples include taxpayers who:
In many cases, taxpayers correctly disclosed dividend income but were unaware that separate PFIC reporting could still be required.
The answer depends on the facts.
Whether Form 8621 is required depends on several factors, including:
Because the analysis can be technical, taxpayers should avoid assuming that all foreign funds are treated identically.
Many NRIs only become aware of Form 8621 after:
If Form 8621 should have been filed but was omitted, taxpayers should evaluate their options promptly rather than attempting piecemeal corrections without understanding the broader compliance implications.
Where appropriate and available, the Streamlined Filing Compliance Procedures may provide a path to correct missed reporting as part of a broader voluntary compliance submission.
The Foreign Bank Account Report (FBAR) is among the most frequently overlooked international reporting requirements for NRIs.
Unlike an income tax return, the FBAR is an information return filed separately with the US government.
Many taxpayers mistakenly believe that only taxable accounts must be reported. In reality, the reporting obligation is based on qualifying foreign financial accounts and applicable filing thresholds, not whether the income is taxable.
Depending on the facts, taxpayers should evaluate whether they hold:
Each account should be reviewed based on the applicable FBAR rules and reporting thresholds.
Some of the most common errors include:
These mistakes frequently arise from misunderstanding the reporting rules rather than intentional non-compliance.
Form 8938, filed with the US tax return, is another important international reporting requirement.
Many taxpayers incorrectly assume that filing an FBAR automatically satisfies all foreign asset reporting obligations. However, the FBAR and Form 8938 serve different purposes and have different reporting requirements.
Depending on the taxpayer's circumstances, both filings may be required for the same tax year.
Depending on the applicable rules and filing thresholds, Form 8938 may require disclosure of certain foreign financial assets, including:
Determining whether Form 8938 applies requires a review of both the type and value of the assets held.
Many NRIs confuse these two reporting requirements.
|
FBAR |
Form 8938 |
|
Filed separately from the tax return |
Filed with the income tax return |
|
Covers reportable foreign financial accounts |
Covers specified foreign financial assets |
|
Administered under FinCEN |
Administered by the IRS |
|
Different reporting rules |
Different filing thresholds |
|
May be required even when Form 8938 is not |
May be required even when FBAR is not |
Because the rules differ, filing one does not automatically eliminate the need to file the other.
Another area that often surprises NRIs involves Forms 3520 and 3520-A.
These forms generally relate to certain foreign trusts, gifts, inheritances, and other specified international transactions.
Not every taxpayer with foreign assets needs these forms, but they become relevant in specific circumstances.
Examples may include:
Because these rules are highly technical, professional analysis is often necessary before concluding whether reporting is required.
Some NRIs own businesses in India while living in the United States.
Depending on the ownership structure, additional international reporting may apply.
Examples include:
Additional information returns may be required in these situations, depending on ownership percentages, control, and other statutory requirements.
Many taxpayers focus only on reporting foreign income.
However, US international tax compliance has two separate components:
A taxpayer may correctly report all foreign income yet still have incomplete international reporting if required information forms were omitted.
Conversely, filing an information return does not eliminate the obligation to report taxable income.
Both aspects should be reviewed together.
Rahul moved to the United States on an H-1B visa in 2021.
He continued to maintain:
His US CPA reported:
However, the CPA never asked about:
After changing advisors in 2026, Rahul discovered that while most of his income had been reported correctly, several international information filings had been missed.
Situations like Rahul's are not uncommon, particularly where taxpayers receive advice from professionals who do not regularly handle cross-border India-US tax matters.
Before evaluating whether the Streamlined Filing Compliance
Procedures are appropriate, taxpayers should gather records such as:
Having complete documentation allows for a more accurate assessment of filing obligations and helps identify any missing information returns.
Taxpayers who discover missing international reporting sometimes rush to correct individual forms without understanding the broader compliance implications.
Each situation should be evaluated holistically rather than on a form-by-form basis.
International tax compliance is interconnected.
For example, correcting a missed PFIC filing may also require reviewing:
Addressing only one issue while overlooking others may result in an incomplete compliance position.
Accordingly, taxpayers should review their entire international reporting profile before deciding on the most appropriate course of action.
Once a taxpayer determines that they may be eligible for the IRS Streamlined Filing Compliance Procedures, the next step is to prepare a complete and accurate submission.
The goal is not merely to file missing forms but to present a comprehensive package that corrects prior non-compliance while demonstrating that the failures were non-willful.
Although every taxpayer's facts differ, the process generally follows these stages.
The first step is to determine when your US tax reporting obligations began.
For NRIs, this often depends on factors such as:
This analysis helps determine the years for which US worldwide income and international reporting obligations may have applied.
Next, review previously filed US tax returns to identify any omissions.
Common areas include:
This review should be comprehensive rather than limited to a single issue.
Accurate reporting depends on complete records.
Documents commonly reviewed include:
Where records are incomplete, reasonable efforts should be made to obtain supporting documentation before preparing amended returns.
The next step is preparing the required amended or delinquent US tax returns.
Depending on the taxpayer's facts, this may involve:
Accuracy is critical because all related information should be internally consistent.
The submission may also include previously omitted international information returns such as:
The forms required depend entirely on the taxpayer's circumstances and should not be assumed based on another person's situation.
One of the most important components of a Streamlined Filing submission is the non-willful certification.
This is not a standard form letter.
Instead, it is a factual explanation describing why the reporting failures occurred.
An effective certification generally explains:
The certification should be truthful, complete, and tailored to the taxpayer's actual circumstances.
Once all returns, information forms, certifications, and supporting documentation have been prepared, the submission is made following the applicable IRS procedures.
After submission, taxpayers should retain copies of:
Good recordkeeping can be valuable if questions arise later.
Example 1 – H-1B Software Engineer
An engineer moved from Bengaluru to California in 2020.
His CPA reported:
However, the CPA did not ask about:
After changing tax advisors, he discovered that several years of FBAR, Form 8938, and PFIC reporting had been omitted.
Following a review of his facts, he was able to assess the appropriate compliance options and regularize his reporting.
A Green Card holder relocated permanently to India.
Before leaving the US, she learned that her Indian investments had never been reported on US tax returns.
Rather than waiting until after her move, she reviewed her filing history and addressed the outstanding reporting issues while professional records were still readily available.
Early planning helped simplify the compliance process.
Can I use the Streamlined Procedures if I already filed my US tax returns?
Possibly. Many taxpayers have filed timely tax returns but later discover that foreign income or international information forms were omitted.
Eligibility depends on the facts of each case.
The Streamlined Filing Compliance Procedures may provide a path for eligible taxpayers to correct previously omitted FBAR filings as part of a broader compliance submission.
Indian mutual funds often require additional US tax analysis because many are generally treated as PFICs.
A review of your investments and prior filings can help determine the appropriate reporting obligations.
Even where foreign tax credits eliminate US income tax, international information reporting obligations may still exist.
The absence of additional tax does not automatically eliminate reporting requirements.
That depends on your circumstances.
If multiple reporting obligations were missed, addressing only one form may not fully resolve your compliance position.
A comprehensive review is generally advisable.
Potentially, yes.
Eligibility depends on factors such as residency, filing history, and whether the non-compliance was non-willful.
Visa category alone does not determine eligibility.
Each taxpayer's facts, residency status, and filing history should be evaluated individually.
Receiving an IRS notice may affect the available compliance options.
Professional advice should be obtained promptly before making any submission.
Although interest on NRE accounts may receive favorable tax treatment in India, US reporting obligations are determined under US tax law.
Taxpayers should evaluate whether those accounts are reportable.
Possibly.
The answer depends on the type of asset, its value, and the applicable US reporting rules.
Many taxpayers unintentionally create additional issues by trying to resolve only part of the problem.
Common mistakes include:
Taking a structured approach can help reduce these risks.
International tax compliance involves the interaction of US tax law, Indian tax law, exchange rates, foreign tax credits, information reporting, and cross-border investment structures.
A single taxpayer may simultaneously need advice on:
Reviewing these issues together often provides a more complete understanding of the taxpayer's compliance position.
Navigating US international tax compliance requires more than preparing forms. It requires understanding the interaction between US tax law, Indian tax law, DTAA provisions, PFIC reporting, foreign tax credits, and cross-border financial planning.
At Dinesh Aarjav & Associates, our India-US tax team assists NRIs, H-1B professionals, Green Card holders, US citizens, and returning Indians with:
With over 25 years of experience and dedicated India-US tax professionals, we help clients become compliant while planning for their long-term cross-border tax obligations.
For many NRIs, discovering a missed FBAR, PFIC filing, or Form 8938 requirement can feel overwhelming. Fortunately, an honest mistake does not necessarily mean there is no path forward.
The IRS Streamlined Filing Compliance Procedures offer eligible taxpayers an opportunity to correct past mistakes and move toward full compliance. However, every case is unique, and the appropriate course of action depends on a careful review of the taxpayer's residency, filing history, investments, and reporting obligations.
Addressing these issues proactively before they become more complex can help taxpayers understand their obligations and make informed decisions with confidence.
CA Sanyam Goel, CPA (USA), FCA, and CISA, specializes in India–US cross-border taxation, NRI tax advisory, US tax compliance, transfer pricing, and international regulatory matters. He assists clients with US and Indian tax obligations, cross-border reporting requirements, and strategic tax planning for global investments and transactions.


.webp)