WhatsApp
 Call Us
 Email Us
 Whatsapp Community

Would you like to schedule a call back
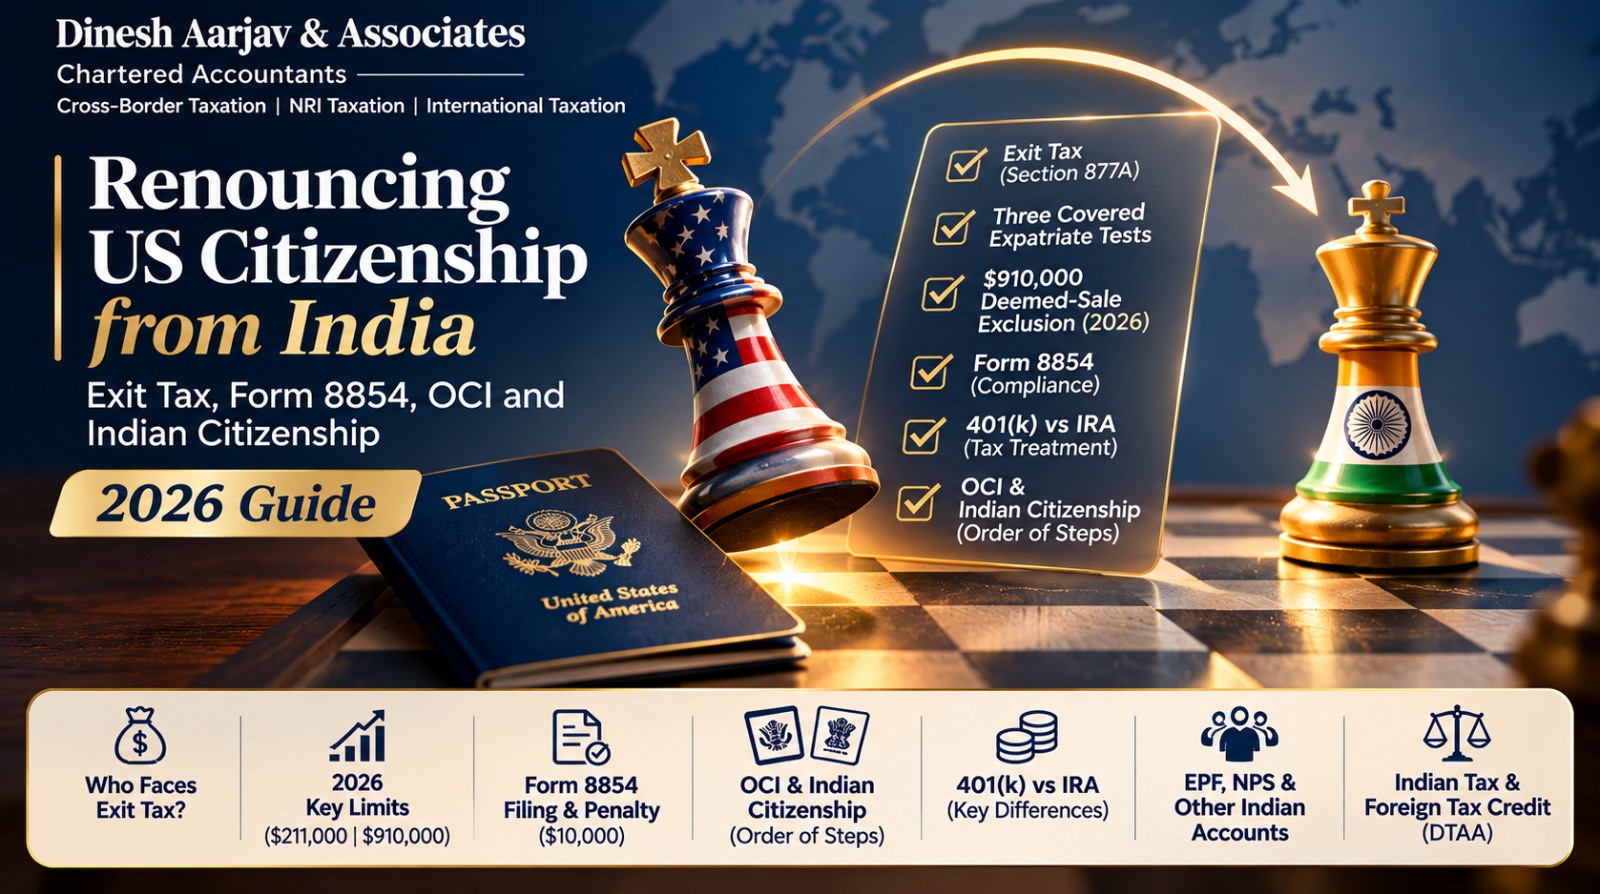


Quick answer: Renouncing US citizenship ends future US tax on your worldwide income, but you may face a one-time exit tax under Section 877A if you are a "covered expatriate". For 2026 you are covered if your net worth is $2 million or more, your average annual US income tax for the last five years exceeds $211,000, or you cannot certify on Form 8854 that you were fully US tax compliant for those five years. A covered expatriate is treated as having sold everything the day before renouncing, with the first $910,000 of net gain excluded. IRAs are treated as fully withdrawn on that day, and 401(k) payments face 30% US withholding for life. The State Department fee is now $450, down from $2,350 since 13 April 2026. For Indian-origin Americans there is a second issue: India does not allow dual citizenship. If you want an Indian passport again, the order in which you renounce and apply matters. Done in the wrong order, you can be left without any citizenship.
This guide is for US citizens of Indian origin living in India, or planning to, who are thinking about giving up their US citizenship. That covers naturalised Americans who moved back, US-born children of Indian parents who grew up or settled in India (often called "accidental Americans"), and families weighing renunciation as part of retirement planning in India. If you hold a green card rather than citizenship, the same exit tax rules apply once you are a long-term resident. Our guide to the US exit tax for green card holders covers that case.
The US taxes its citizens on worldwide income wherever they live. A US citizen who is resident in India files a full US return every year and reports Indian bank accounts on FBAR and FATCA Form 8938. They also face punitive US tax on Indian mutual funds, which count as PFICs and need Form 8621. On top of that, they often struggle to open Indian brokerage or bank accounts because of FATCA. Over time, many decide the passport is not worth the compliance. The decision is permanent, though, and the cost is decided by facts you can often change in the year or two before you act.
|
Item |
2026 figure |
Source |
|
Net worth test |
$2,000,000 or more on the expatriation date (not indexed) |
Section 877(a)(2)(B) |
|
Tax liability test |
Average annual net US income tax for 2021–2025 above $211,000 |
Rev. Proc. 2025-32 |
|
Certification test |
Unable to certify five years of US tax compliance on Form 8854 |
Section 877(a)(2)(C) |
|
Deemed-sale exclusion |
First $910,000 of net gain |
Rev. Proc. 2025-32 |
|
Gift tax annual exclusion (relevant to Section 2801) |
$19,000 per recipient |
Rev. Proc. 2025-32 |
|
State Department CLN fee |
$450 (from 13 April 2026; previously $2,350) |
Final rule, Federal Register, 13 March 2026 |
|
Penalty for not filing Form 8854 |
$10,000 |
Section 6039G |
Meeting any one of the three tests makes you a covered expatriate. Meeting none means no exit tax, although you still file Form 8854.
This counts worldwide assets at market value on your expatriation date. That includes your Indian flat, ancestral property you have an interest in, Indian mutual funds, EPF and NPS balances, gold and your share of joint accounts. The $2 million threshold is fixed by statute and is not adjusted for inflation. Every year of rising Indian property prices brings more families over it.
This looks at your average annual net US income tax for the five years before the year you expatriate, after foreign tax credits. It is your tax, not your income. A US citizen living in India who claims credit for Indian tax often has a low net US tax bill and passes this test easily.
On Form 8854, you must certify under penalty of perjury that you have met every US federal tax obligation for the five years before expatriation. That includes information returns, not just income tax. This is the test that catches most Indian-origin Americans. A missing Form 8621 for an Indian mutual fund, a missing FBAR, or an unfiled Form 3520 for a gift from your parents in India can make you a covered expatriate even with a modest net worth. You fix it by bringing those years into compliance before you renounce. The IRS's Streamlined Foreign Offshore Procedures, or its relief procedures for certain former citizens, may be available depending on your facts.
There are two exceptions to the net worth and tax tests (not the certification test):
The first looks tailor-made for US-born children of Indian parents, but it usually fails for one reason. India does not automatically make a child born abroad an Indian citizen. Citizenship by descent requires the birth to be registered at an Indian mission, and India does not allow the child to keep another passport. Most US-born Indians therefore hold an OCI card, not Indian citizenship, and OCI is not citizenship. If you were not an Indian citizen at birth, this exception does not apply.
Not sure whether you're a covered expatriate? Most of the cost of renouncing is decided before your consular appointment. We'll check your five-year compliance, value your worldwide net worth and estimate the deemed-sale gain on each asset before you book anything. Book a pre-renunciation review.
A covered expatriate is treated as having sold every asset at fair market value on the day before the expatriation date. Your US and Indian shares, Indian mutual funds, your Indian flat and any business interests all count. The net gain is taxed in the year you expatriate, after the first $910,000 is excluded. Losses offset gains, and the exclusion is spread proportionally across your gains. You can elect to defer the tax on particular assets until you actually sell them, but you must give the IRS security and pay interest, and the election cannot be undone.
Your expatriation date is normally the day you take the oath of renunciation before a US consular officer. The State Department later confirms it with a Certificate of Loss of Nationality (CLN).
Retirement accounts are not part of the deemed sale. They follow their own rules, and the type of account matters a great deal.
|
Account |
Treatment for a covered expatriate |
|
401(k), 403(b), US pension (eligible deferred compensation, if you file Form W-8CE) |
Not taxed at expatriation. Every future payment faces 30% US withholding, with no treaty reduction |
|
Traditional IRA, Roth IRA, HSA, 529 plan (specified tax-deferred accounts) |
Treated as fully withdrawn the day before expatriation. The taxable portion is taxed in the expatriation year, with no 10% early withdrawal penalty |
|
Non-US retirement plans such as EPF, NPS or a foreign employer plan (generally ineligible deferred compensation) |
Present value generally treated as received the day before expatriation and taxed then |
|
Interest in a non-grantor trust |
30% withholding on future taxable distributions |
The IRA rule surprises many people. A $300,000 traditional IRA becomes $300,000 of ordinary income in the year you renounce, even though you have not touched it. Whether to empty retirement accounts before renouncing, spread withdrawals over several years, or leave the 401(k) to the 30% withholding regime depends on your income in both countries. Getting the order right is often worth more than anything else in the plan.
India does not recognise the US deemed sale. Renouncing US citizenship is not a "transfer" under Indian law, so there is no Indian tax at expatriation and your Indian cost basis does not change. When you later sell your Pune flat or your mutual funds, India taxes the real gain from your original cost.
This creates a timing mismatch. The US may tax a deemed gain on your Indian property in the year you renounce, and India taxes the actual gain years later. A foreign tax credit in India is normally matched to the year the income is taxed in India. Credit for US exit tax paid years earlier on a gain that existed only on paper is uncertain at best. If the exclusion does not shelter your Indian assets, consider selling some of them before you renounce, while you are still a US citizen. Both countries then tax the same gain in the same year, and the credit under the India–US DTAA works as intended. Whether that helps depends on your residential status in India and the asset mix, and it is the part of the plan most worth modelling.
Holding Indian property, mutual funds or EPF and planning to renounce? We prepare the US and Indian sides together, so a sale before renunciation, the exit tax and the Indian capital gains all line up. Talk to a cross-border tax advisor.
Rahul became a US citizen in 2012 and moved to Pune in 2023. He is now Resident and Ordinarily Resident in India. He is fully compliant on his US filings, including Form 8621 for his Indian mutual funds. The day before his 2026 expatriation date, he holds:
|
Asset |
Market value |
Cost basis |
Treatment |
|
US brokerage shares |
$900,000 |
$350,000 |
Deemed sale: $550,000 gain |
|
Indian mutual funds |
$250,000 |
$150,000 |
Deemed sale: $100,000 gain |
|
Pune flat |
$350,000 |
$150,000 |
Deemed sale: $200,000 gain |
|
Cash |
$150,000 |
— |
None |
|
401(k) |
$400,000 |
— |
30% withholding on future payments |
|
Traditional IRA |
$100,000 |
— |
Treated as fully withdrawn: $100,000 ordinary income |
|
Net worth |
$2,150,000 |
Covered expatriate (net worth test) |
His deemed-sale gains total $850,000, which is below the $910,000 exclusion, so he owes no tax on the deemed sale. The real costs are elsewhere. His IRA adds $100,000 of ordinary income in 2026, and every 401(k) payment for the rest of his life is withheld at 30%. If he had brought his net worth below $2 million before renouncing, for example through gifts to family made while Section 2801 does not yet apply, he would not have been covered at all, and neither cost would apply.
Now change one fact. Suppose Rahul's net worth were $1.6 million but he had never filed Form 8621 for his mutual funds. He would still be a covered expatriate, through the certification test. The fix, filing the missing forms before renouncing, costs far less than the consequences.
The tax rules come from the US. Whether you still have a citizenship afterwards depends on India's rules, and this is where Indian-origin Americans most need to plan. India does not allow dual citizenship, and an OCI card is not citizenship.
|
Your situation |
What happens when you renounce US citizenship |
|
You hold another foreign citizenship (e.g. UK) |
You remain a citizen of that country; your OCI card stays valid, though it should be updated with your new passport |
|
You were an Indian citizen who naturalised in the US |
Your Indian citizenship ended when you naturalised. To become Indian again, you apply for citizenship by registration, typically after holding OCI for five years and living in India for a year |
|
You were born in the US and never held Indian citizenship |
You need another citizenship before you renounce, or you will be stateless. The US allows renunciation even if it leaves you stateless, but warns strongly against it |
In practice, the safe order is to apply for Indian citizenship by registration first and get it approved. Then you renounce US citizenship, and only after that does India issue your citizenship certificate. The date you take the US oath is also your expatriation date for tax, so the Indian citizenship timeline and the US tax planning have to be coordinated. Your OCI card is surrendered when you become an Indian citizen. Take advice from an immigration lawyer on the citizenship steps. We coordinate the tax side so the expatriation date falls where it should.
Renunciation must be done in person before a US consular officer, at the US Embassy in New Delhi or a US consulate in India that offers the service, by appointment. The process usually involves:
On the tax side, you file a final dual-status US return for the year of expatriation, with Form 8854 attached, and that year's FBAR. If you are a covered expatriate, the return includes the deemed-sale gain, the IRA deemed distribution and any deferral election.
Our guide to filing US taxes after moving back to India covers the annual obligations you have until the day you renounce.
The most expensive is renouncing before fixing past filings, which makes someone a covered expatriate through the certification test when they would otherwise have passed. Others we see often:
The last one is not a tax mistake, but it is the hardest to undo.
Renouncing is a one-time decision, but the tax cost is set by choices you make in the year or two before it. Dinesh Aarjav & Associates prepares US and Indian returns for US citizens living in India and coordinates the whole exit with your Indian tax position.
Our pre-renunciation review covers:
Book your pre-renunciation review or message us on WhatsApp. Also see our US tax return services for NRIs, our NRI & OCI services and our guide to returning to India.
CA Priyal Goel Jain is a Partner at Dinesh Aarjav & Associates and a leading expert in India–US cross-border taxation, NRI taxation, and international tax advisory. She advises NRIs, OCIs, and global families on complex cross-border transactions, tax planning, foreign asset reporting, and multi-jurisdictional compliance matters.
Stay in the loop, subscribe to our newsletter and unlock a world of exclusive updates, insights, and offers delivered straight to your inbox.
.webp)