WhatsApp
 Call Us
 Email Us
 Whatsapp Community

Would you like to schedule a call back
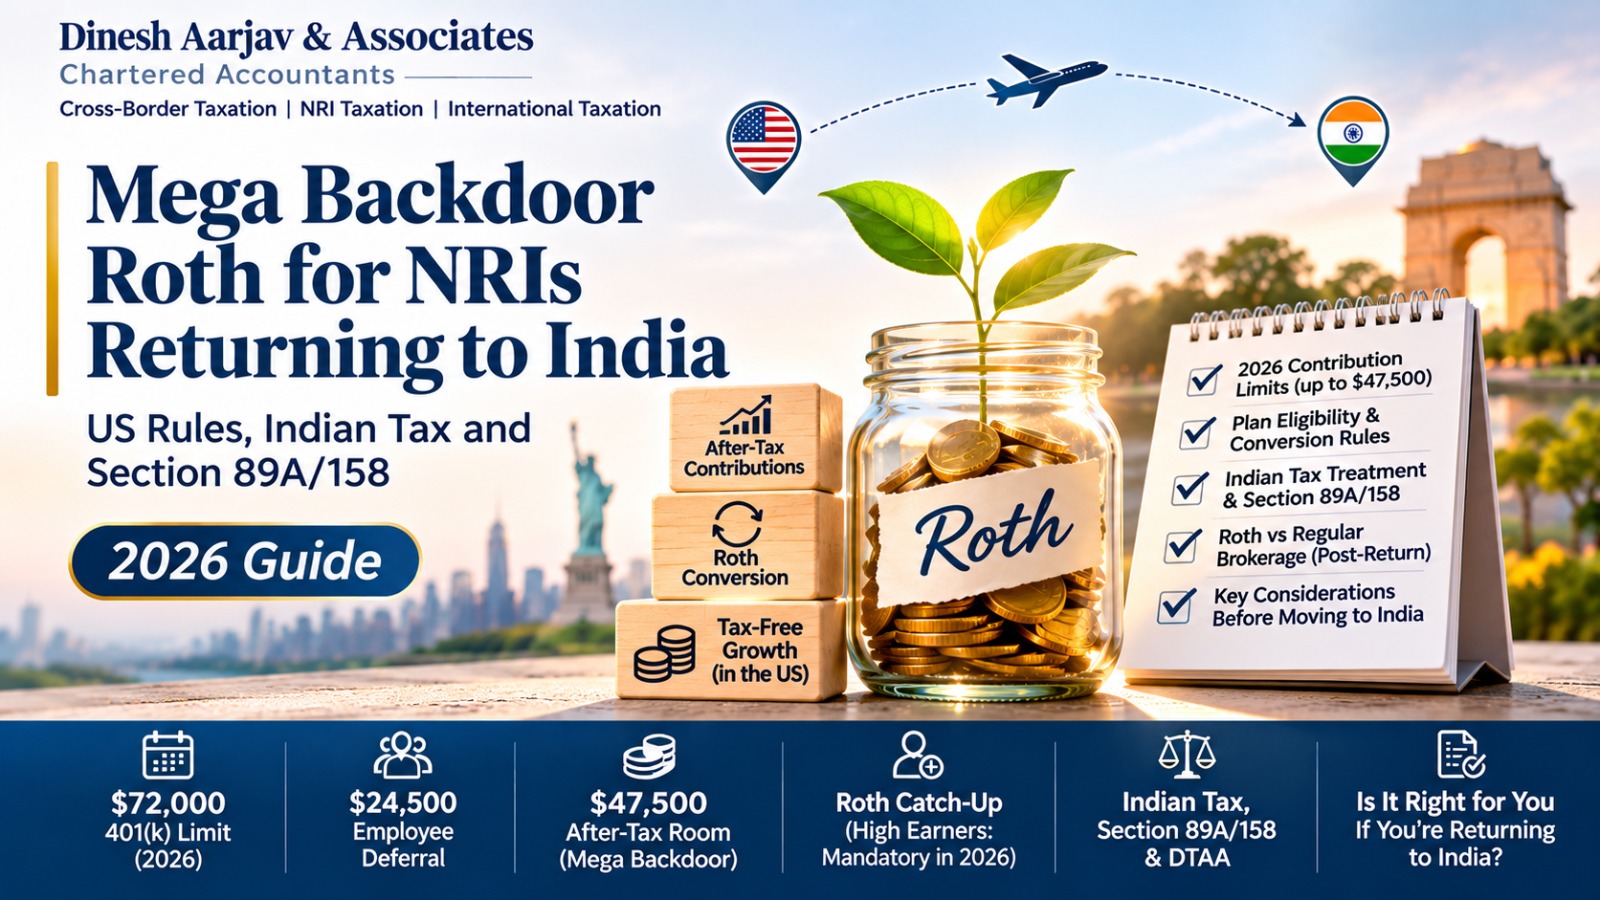


A mega backdoor Roth lets you put up to $47,500 of after-tax money into your 401(k) in 2026 and convert it to Roth, so future growth is tax-free in the US. That number is the $72,000 total limit, minus your $24,500 deferral and any employer contributions. For a mega backdoor Roth for NRIs heading back to India, the catch is simple: India has no Roth concept.
Here's the short version of what that means:
So is it worth doing? If you'll stay in the US for five years or more, or you're a US citizen or green card holder, yes, usually. If you expect to move back within about two years, it often adds little over a regular brokerage account.
It's a way to get far more money into Roth accounts than the normal limits allow. Let's walk through the two steps.
Once it's in Roth, qualified withdrawals (growth included) are free of US federal tax. The strategy is legal and has no income limit. What holds people back is their employer's plan, and that's where most get stuck.
You can add up to $47,500 in after-tax money if your employer contributes nothing. The ceiling comes from the Section 415(c) limit, which covers your deferrals, employer contributions and after-tax contributions together.
| 2026 limit (IRS Notice 2025-67) | Amount |
|---|---|
| Total 401(k) contributions, all sources (Section 415(c)) | $72,000 |
| Employee deferral, pre-tax or Roth (Section 402(g)) | $24,500 |
| Max after-tax room with no employer contribution | $47,500 |
| Catch-up, age 50+ (on top of $72,000) | $8,000 |
| "Super" catch-up, age 60 to 63 (replaces the $8,000) | $11,250 |
| Roth or traditional IRA contribution | $7,500 (plus $1,100 at 50+) |
Your after-tax room is $72,000 minus your own deferral minus whatever your employer puts in. Say you defer $24,500 and your employer adds a $9,000 match. You'd have $38,500 of after-tax room left.
There's one 2026 change for higher earners. If your FICA wages from the employer were above $150,000 last year, your catch-up contributions now have to go in as Roth. For many senior NRIs, part of their savings is Roth money whether they planned it or not, so the Indian tax questions below apply to it too.
Only if it has two features, and you'll find both in your plan's Summary Plan Description (SPD).
Without the second feature, your after-tax money sits in the 401(k) earning taxable growth until you leave the employer. Also, highly paid employees should know that if the plan fails its yearly nondiscrimination test, some after-tax contributions may be refunded.
Converting your after-tax contributions costs nothing, because you've already paid tax on that money. But any growth between contributing and converting is taxed as ordinary income at conversion. That's why the best plans convert automatically after every paycheck, so almost nothing builds up.
The mega backdoor uses after-tax 401(k) contributions and allows far more money. The backdoor Roth IRA uses a non-deductible IRA contribution and is much smaller.
| Point | Mega backdoor Roth | Backdoor Roth IRA |
|---|---|---|
| How it works | After-tax 401(k) contributions, then converted to Roth | Non-deductible traditional IRA contribution, then converted to Roth IRA |
| 2026 maximum | Up to $47,500 | $7,500 ($8,600 at 50+) |
| Needs employer plan support | Yes | No |
| Pro-rata rule | Does not apply | Applies if you hold any pre-tax IRA money |
| Income limit | None | None |
| Requires US earned income | Yes, through your US employer | Yes, you need taxable compensation |
The pro-rata rule catches many returning NRIs. If you rolled an old 401(k) into a traditional IRA, a backdoor Roth IRA conversion is partly taxable, because the IRS treats all your pre-tax and after-tax IRA money as one pool. Our guide to IRAs for NRIs covers this in more detail.
Roth accounts have two separate five-year clocks, and people often mix them up.
The second point matters more than most articles admit. With a mega backdoor done properly, your after-tax contributions convert with little or nothing taxed. Roth IRA withdrawals also come out in a fixed order: contributions first, then conversions (oldest first), then earnings. So the money you put in can usually be taken out of a Roth IRA without US tax or penalty, even before 59½. What stays locked is the growth.
Roth 401(k) money doesn't follow these ordering rules. Withdrawals are split proportionally between contributions and earnings. That's why many people roll their Roth 401(k) into a Roth IRA when they leave their employer. Since 2024, Roth 401(k)s, like Roth IRAs, have no required minimum distributions during the owner's lifetime.
Moving back to India in the next few years? Before you put another dollar into after-tax 401(k) contributions, we can check whether a Roth still makes sense for you, based on your move date, residential status and plan. Book a pre-move retirement review.
It depends on your residential status, and for an ROR the growth is taxable. India's Income-tax law has no tax-free retirement wrapper like a Roth. There's also no CBDT circular or court ruling on how a US Roth is taxed, so what follows is how we read the law.
| Status in India | Indian tax on Roth growth and withdrawals |
|---|---|
| Non-Resident (NR) | Not taxable. Foreign-source income is outside Indian tax |
| Resident but Not Ordinarily Resident (RNOR) | Generally not taxable if the withdrawal is paid and kept outside India |
| Resident and Ordinarily Resident (ROR) | Growth is taxable. Contributions come back as return of capital and are not taxable |
Only the growth inside a Roth counts as income for Indian purposes. The money you put in, including converted after-tax contributions, is your own capital coming back.
To prove the split, you'll need your Form 5498 records, Form 8606 (which tracks after-tax basis in IRAs), plan statements showing after-tax contributions, and conversion confirmations. India has no prescribed method, so these records are your evidence. Keep them indefinitely.
Probably not. Section 89A lets a returning resident defer Indian tax on income building up in a foreign retirement account. It now sits in the Income-tax Act, 2025 as Section 158, with Form 40 replacing Form 10-EE.
The tax is deferred until the year the foreign country taxes the withdrawal. The relief only covers a "specified account", meaning one the foreign country taxes on withdrawal rather than as income accrues. A qualified Roth withdrawal is never taxed in the US, so the event the relief is waiting for never happens. Most practitioners treat Roth accounts as outside it. We explain the relief for traditional accounts in our guide to the Section 89A to Section 158 changes.
That leaves an open question for an ROR: when is the growth taxed? There are two views.
Neither view has been tested in court. Which one you take, and how you disclose it, is a judgment call to make with your return preparer and document in the return.
With a traditional 401(k) or IRA, the US taxes withdrawals and India gives credit for that tax. With a qualified Roth withdrawal, the US charges nothing, so there's nothing to credit. Any Indian tax on Roth growth is a real cost.
On a non-qualified withdrawal, the US taxes the earnings and may add the 10% penalty. Credit for the income tax part is claimed on Form 67 under the India-US DTAA. Whether India gives credit for the 10% penalty is unclear.
As an ROR, you must report Roth IRA and Roth 401(k) accounts in Schedule FA of your ITR, like any other foreign asset, whether or not anything is taxable that year. Leaving them out can lead to a ₹10 lakh penalty under the Black Money Act. Our post on what to report in your ITR lists the schedules.
Already back in India with Roth money? We'll work out your residential status, the contributions-versus-growth split, how the growth should be reported and your Schedule FA disclosure, so your ITR takes a position you can defend. Get your Roth accounts reviewed.
Let's put real numbers on it. Kavya, 36, works in Seattle on an H-1B. In 2026 she defers $24,500 pre-tax and her employer matches $9,000, leaving $38,500 of after-tax room. Her plan converts automatically after every paycheck. She expects to move back to Bengaluru in mid-2027.
| Question | If Kavya stays in the US 6+ years | If Kavya moves to India in 2027 |
|---|---|---|
| US tax on Roth growth | None on qualified withdrawal after 59½ | None on qualified withdrawal, but that's 23 years away |
| US tax with a normal brokerage account instead | Capital gains tax on sale | Usually none, since a non-resident alien generally isn't taxed on US capital gains |
| Indian tax on growth | Not relevant while she's NR | Taxable once ROR, with no foreign tax credit |
| Access to the money | Contributions available through Roth IRA ordering rules | Contributions available; growth locked until 59½ |
| Verdict | Strong fit | Small benefit at best; flexibility may matter more |
For a US resident, the appeal is tax-free growth compared with a taxable account. Once Kavya is a non-resident alien, a normal US brokerage account already avoids US capital gains tax in most cases, and India taxes the gains either way. So the Roth's US advantage mostly disappears.
What's left, mainly no US tax on dividends inside the account, has to be weighed against the money being locked away and the unclear Indian treatment. If she later returns to the US, or becomes a green card holder or citizen, the answer changes. A US citizen or green card holder keeps the full US benefit wherever they live.
It's usually worth it if all of these apply:
It's usually a poor fit if you're leaving within about two years, you'll retire in India as an ROR, or you're leaving the US for good. In that case, money that would have gone into after-tax 401(k) contributions often does better in a taxable account. Ireland-domiciled ETFs are worth a look there, since they also reduce US estate tax exposure. See our guide to Ireland-domiciled ETFs for NRIs.
Possibly. If you hold a traditional IRA or old 401(k), converting some of it to Roth in a lower-income US year can lock in a low US tax rate.
Once you're a non-resident alien, the US rate on the conversion and your treaty position both change. A conversion after you become ROR also adds a Roth that India may tax on growth with no credit. The timing between your last US year and your RNOR years is where most of the planning value lies, and it needs both countries modelled together.
Here's a simple checklist.
The most common one is assuming a Roth is tax-free in India because it's tax-free in the US. Here are others we often see:
On the US side, people forget that Roth 401(k) withdrawals don't follow the Roth IRA ordering rules.
Roth accounts are the least clear part of a returning NRI's retirement planning, because Indian law has never addressed them. Dinesh Aarjav & Associates prepares US and Indian returns for NRIs and returning Indians together, so your contributions, conversions, residential status and Indian disclosures all line up.
Our retirement account review for returning NRIs covers:
Book your retirement account review or message us on WhatsApp. Also read: 401(k) taxation in India and Section 158, the ITAT Mumbai ruling on Form 10-EE, our US tax return services for NRIs and our guide to returning to India.
This article is for general information and reflects the law as of November 2026. It is not tax advice for your specific situation.
CA Priyal Goel Jain is a Partner at Dinesh Aarjav & Associates and a leading expert in India–US cross-border taxation, NRI taxation, and international tax advisory. She advises NRIs, OCIs, and global families on complex cross-border transactions, tax planning, foreign asset reporting, and multi-jurisdictional compliance matters.
Stay in the loop, subscribe to our newsletter and unlock a world of exclusive updates, insights, and offers delivered straight to your inbox.
.webp)