WhatsApp
 Call Us
 Email Us
 Whatsapp Community

Would you like to schedule a call back
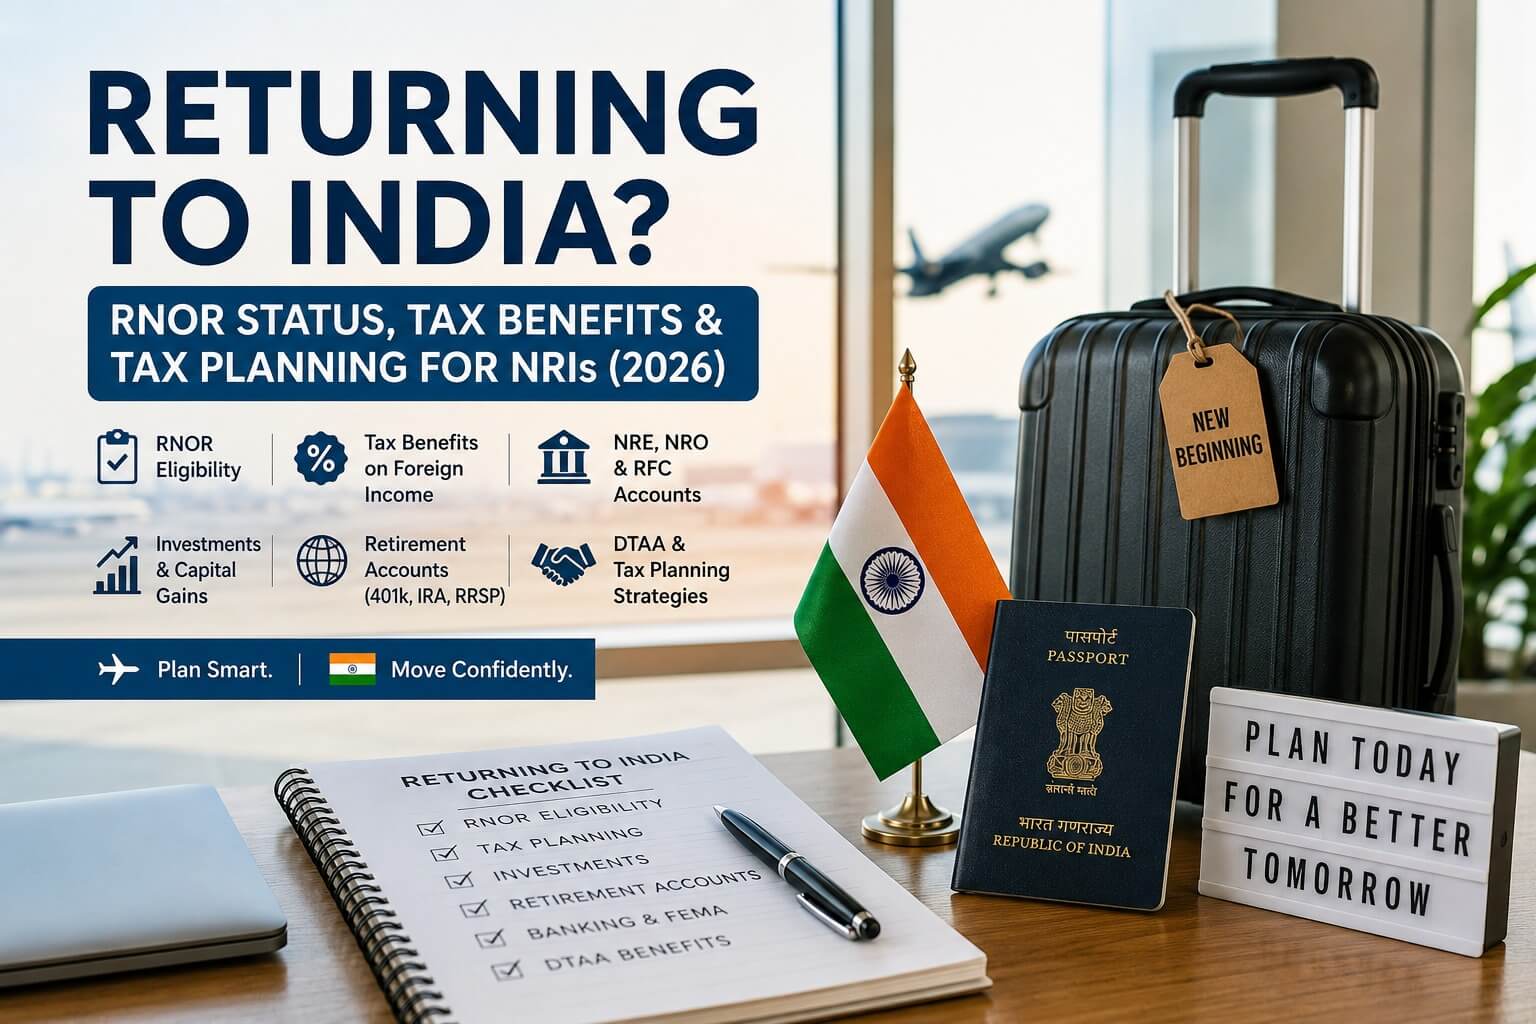


RNOR status (short for Resident but Not Ordinarily Resident) is a temporary tax status in India for people moving back after years abroad. While you hold it, India generally taxes your Indian income but leaves most of your foreign income alone. For most people, it lasts about two to three years.
So if you're heading home from the US, Canada, the UK, the UAE, or Singapore, this is one of the first things worth getting your head around. It isn't a blanket tax holiday. But if you plan around it, it gives you breathing room to sort out your global money before India starts taxing all of it.
Let's walk through how it works, who qualifies, and how to make the most of it.
RNOR is the middle step between being an NRI and being a fully settled Indian resident. It exists to give returning Indians a soft landing instead of an overnight jump into worldwide taxation.
Indian tax law has three residential statuses:
Most returning NRIs move along a path from NRI to RNOR to ROR. Knowing where you sit each year is the whole game.
A quick note on the law: from 1 April 2026, the Income-tax Act, 2025 replaces the Income Tax Act, 1961. It uses the term "tax year" instead of "previous year," but the RNOR conditions are broadly the same. Everything below still applies.
INDIAN INCOME TAX ACT.2025
Work out whether you're a Non-Resident, Resident but Not Ordinarily Resident (RNOR), or Resident and Ordinarily Resident (ROR) for a given financial year.
STEP 1 · YOUR STAY THIS YEAR
This decides whether the 120-day relaxed rule applies to you.
STEP 2 · YOUR STAY IN PRIOR YEARS
Add up your days present across those four financial years. Used for the 60/120-day test above, where applicable.
Add up your days present across those seven financial years.
Your residential status for the year
—
Get this confirmed for your exact case
Our tax team can review your numbers and next steps — first call is free.
The easiest way to see why RNOR status matters is to put the three statuses side by side. Look at the middle row. That's where the planning value lives.
| Status | Income received in India | Income earned in India | Foreign income |
|---|---|---|---|
| NRI | Taxable | Taxable | Generally not taxable |
| RNOR | Taxable | Taxable | Generally not taxable (with exceptions) |
| ROR | Taxable | Taxable | Taxable |
In short, an RNOR gets taxed much like an NRI, even though they're technically a resident. The main exceptions are income from a business controlled from India, a profession set up in India, and foreign income that's first received in India. We'll cover those in a bit.
Qualifying for RNOR status is a two-step check, done fresh for every financial year (April to March). First you need to be a resident. Then you need to pass at least one RNOR test.
You're generally an Indian resident for the year if either of these is true:
If neither applies, you're still an NRI for that year, and RNOR doesn't come into it yet.
Once you're a resident, you're RNOR (not ROR) if you meet either one of these:
You only need one. You become ROR only when you fail both at the same time.
Here's an example. Say work trips and family visits pushed your India days over the last seven years to 740. You've failed the second test. But if you were an NRI in 9 of the last 10 years, you pass the first one, so you're still RNOR.
There are two extra rules for Indian citizens and Persons of Indian Origin (PIOs) that came in with the Finance Act 2020 and carry over into the new law:
These mostly affect people who split their time between India and a no-tax country like the UAE.
Every day you're physically in India counts, and that usually includes both your arrival day and your departure day. Keep your passport stamps, boarding passes, and travel records. Being off by even a day or two can flip your status, so work it out from your real dates, not a rough guess.
RNOR status usually lasts two to three financial years. There's no fixed period in the law. It simply depends on how your day counts and past residency play out.
Here's how it typically goes for someone who lived abroad for 10+ years with only short visits home:
That third year is where your landing date really matters. More on that next.
Your move date is a tax decision, not just a logistics one. Because status is decided year by year (April to March), landing a few weeks earlier or later can shift how long you're protected.
A few ways it can play out:
A word of caution on the popular "land after 2 October" advice. It assumes only the 182-day test applies. If you're moving back to india for good (not just visiting) and you've spent 365+ days in India over the past four years, the 60-day test can make you resident even with a late arrival.
The practical takeaway: before you book flights, map your India days against the financial-year calendar for the next three or four years. A shift of a few weeks can change your RNOR window by a full year.
The big RNOR tax benefit is simple: foreign income earned and received outside India generally isn't taxed in India. Here's how that works for the income most returning NRIs have.
Dividends and capital gains on US stocks, ETFs, or other overseas investments are generally outside India's tax net while you're RNOR. Keep in mind your former country may still tax them, depending on its own rules and your citizenship.
Rental income from a home in the US, Canada, UK, UAE, or anywhere else is generally not taxable in India during RNOR, as long as it's earned and received abroad.
Interest on your overseas bank accounts generally stays outside Indian tax while you're RNOR.
If you're paid for work you actually did abroad (for example, final months of salary or a bonus for your overseas role), that's generally not taxable in India as an RNOR.
This one needs the most care. How India treats a 401(k), IRA, Roth IRA, RRSP, RRIF, SIPP, or UK or Australian pension depends on the account type, the country's rules, and the tax treaty (DTAA) between India and that country.
Don't cash out a retirement account just because you're moving. Early withdrawals can trigger penalties and tax abroad. India also has special rules for certain US, UK, and Canadian retirement accounts that can help line up the timing of tax once you become ROR. Use your RNOR years to figure out the best plan before you touch anything.
RNOR status doesn't protect anything that comes from India. Indian-source income is taxed no matter what your status is.
Generally taxable for an RNOR:
Generally not taxable for an RNOR:
Every item on that second list comes with a condition: the income has to genuinely be foreign. If where it comes from, or where it lands, changes, the tax treatment can change too.
This is where returning NRIs most often get caught out. "Foreign" income can still end up taxable in India in a few situations.
Income that's received in India for the first time is taxable in India, even for NRIs. So if a foreign employer or tenant pays straight into your Indian bank account, that income can become taxable.
The fix is easy. Let foreign income land in a foreign account first. Once it's been received abroad, moving that money to India later is just a transfer of your own savings, not new income.
Living in India and working remotely for a foreign company? That salary is usually taxable in India, because the work is being done here. It doesn't matter that your employer and paycheck are overseas. This surprises a lot of people.
If you run a foreign business or freelance practice and make the key decisions from India, its income can be taxed in India even during RNOR. Passive investments in foreign companies you don't control are generally fine.
Some income is treated as arising in India under specific tax rules, even if the activity happens abroad. If you have unusual income streams, get them checked.
Before moving any money during your RNOR years, look at four things: where the income comes from, what kind it is, who controls it, and where it first lands.
Think of RNOR as a planning window, not just a tax break. Here's how returning NRIs commonly use it.
The best returning NRI tax planning happens before you land, not after. Work through this list a few months ahead.
Your tax status and your FEMA status are two separate things. Tax status shifts gradually (NRI, then RNOR, then ROR). FEMA status usually changes as soon as you come back to live in India. That means your banking needs attention right away.
Here's what typically happens to each account:
| Account | What to do |
|---|---|
| NRE account | Convert to a resident account or move funds to an RFC account |
| NRO account | Convert to a regular resident savings account |
| FCNR deposit | Usually let it run to maturity, then move to RFC or resident account |
| PIS / NRI demat | Switch to a resident demat and trading account |
| Foreign bank accounts | You can generally keep them; tell the bank you've moved |
A few things to know:
Getting your return right is how you actually claim the RNOR benefit. Pick the wrong option and you could end up paying tax on income you didn't need to.
Knowing the rules is half the job. Dodging these mistakes is the other half.
RNOR status for returning NRIs doesn't wipe out your taxes. What it does give you is a limited, valuable window to sort out your global finances before India starts taxing everything.
If a move back to India is on the cards, get your status and plan reviewed before you relocate. A few hours of planning now can save you a lot of tax and stress later.
CA Priyal Goel Jain is a Partner at Dinesh Aarjav & Associates and a leading expert in India–US cross-border taxation, NRI taxation, and international tax advisory. She advises NRIs, OCIs, and global families on complex cross-border transactions, tax planning, foreign asset reporting, and multi-jurisdictional compliance matters.


Stay in the loop, subscribe to our newsletter and unlock a world of exclusive updates, insights, and offers delivered straight to your inbox.
.webp)